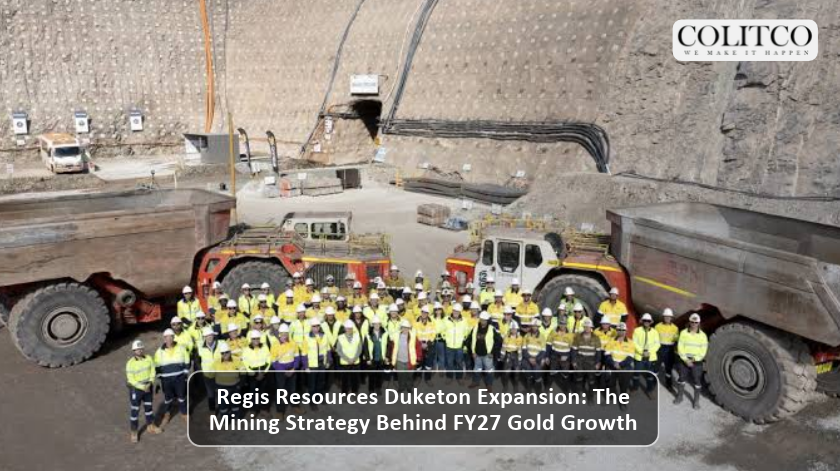
Regis Resources is leaning hard on its Western Australian base. The Duketon Gold Project sits at the centre of that push. Group Regis Resources production guidance for FY27 is 360koz – 400koz. Duketon supplies 240koz – 270koz of it. Tropicana, held at 30%, adds 120koz – 130koz.
Management hosted analysts at Duketon on 2 November 2026. The pitch was plain. Sustain the assets, harvest the cash and invest for the future. The company carries no debt. Cash and bullion stood at $1.3B on 30 September 2026. Shares closed at $6.25 on 30 October 2026, implying a market value near $4.7B, per the Regis Resources investor presentations.
Duketon is wholly owned by Regis. It spans a dominant 2,500km2 land package. Three mills anchor the operation. Garden Well Mill handles 4.0Mtpa of fresh rock. Rosemont Mill takes 2.0Mtpa, and Moolart Well Mill another 2.0Mtpa. A 9MW solar array and a camp round out the site. Because this infrastructure is paid for, growth capital goes further.
What the Duketon Gold Project Holds Today
Duketon South has open pits and underground mines. Its underground Reserves total 12Mt @ 1.8g/t for 714koz. Duketon North adds open pit Reserves of 15Mt @ 0.9g/t for 426koz. All up, Duketon holds Ore Reserves of 1.4Moz and Mineral Resources of 4.0Moz. Group Resources sit at 8.3Moz, with Reserves of 3.9Moz.
Why does that matter? The ore sits near existing mills, so new spending stays limited. Combined mill throughput rose from 7.4Mt in FY25 to 8.1Mt in FY26, a 10% lift. Moolart Well Mill had been in care and maintenance. It has restarted on historic stockpiles, at record gold prices.
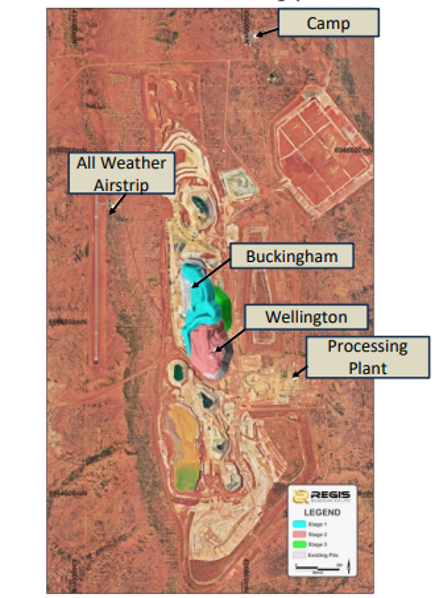
Moolart Well Mill’s restart on historic stockpiles helped lift combined Duketon throughput to 8.1Mt in FY26. [Regis Resources]
Why Duketon Gold Project Output Skews to H2
FY27 will not be a smooth ride. These points explain the shape of the year:
- The cost guide is wide. Group all-in sustaining cost (AISC) is guided at $2,990 – $3,390/oz. This is the key margin measure, so gold prices will decide how much profit is left.
- The second half carries the load. Q1 FY27 output was 83.0koz. Weather and a back-ended mining schedule held it down, so investors should watch the half-year result.
- Tax will dent cash briefly. A catch-up payment of ~$220M – $240M lands in the December quarter. Cash may dip before it rebuilds.
How the Duketon Gold Project Replaces Mined Ounces
Every miner must replace what it digs up. Regis does it cheaply, and the evidence is strong:
- Discovery is low cost. Exploration and resource definition run at about A$76/oz at Duketon. That protects margins when gold prices fall.
- Underground mines keep growing. Underground Ore Reserves are up ~850% since 2019. That holds true even after 475koz was mined out. It shows the mines are expanding, not shrinking.
- New finds sit close to mills. Beamish South added a 270koz Resource, just 4km from Garden Well. Short haul distances mean cheaper mill feed.
Where Regis Resources Gold Production Gains Come From
Growth is not relying on one source. Several levers are working together:
- BuckWell extends mine life. It adds about 223koz over ~5.7 years. It also keeps the restarted Moolart Well Mill busy.
- Proven contractors add stability. MACA has worked the open pits since 2010. Barminco has worked underground since 2019. Steady crews reduce execution risk.
- Tropicana offers higher grade. The Havana underground targets first production in H1 CY2027. That could lift output and lower costs at the joint venture.
When Cash, Dividends and McPhillamys Converge
Cash is already building. It rose $93M in Q1 FY27 to $1.28B. That includes the $51M Vault break fee and comes after $53M in tax. After quarter-end, Regis paid a fully franked final dividend of 20c per share, worth $152M. Total FY26 dividends reached 35cps. That is a 6.5% yield on the $7.72 record date price. Regis has declared ~$850M since 2013. Free cash flow came in at A$1.06 per share in FY26.
Duketon output is weighted to H2, so timing matters. A catch-up tax payment of ~$220M – $240M lands in the December quarter. McPhillamys is the next chapter. Its 1.9Moz Reserve supports ~10 years of production. The PFS shows an NPV5.5% of $1.1 billion and a 21.8% IRR at A$4000/oz. Output averages 190koz a year and peaks at 239koz. Life-of-mine AISC is A$1,718/oz.
On 14 October 2026, the Federal Court ruled the Section 10 declaration invalid. The Minister’s redetermination is still pending. Meanwhile, Regis is progressing the IWL alternative, which avoids the declared area. FID is targeted for H1 CY28. Full details sit in the Regis Resources ASX announcements.
Also Read: China’s Gold Deposits: A Challenge for Australia?
FAQs
Q1: What is Regis Resources’ FY27 production guidance?
A1: Group guidance is 360koz – 400koz. Duketon contributes 240koz – 270koz and Tropicana 120koz – 130koz.
Q2: How much cash does Regis hold?
A2: Regis held $1.3B in cash and bullion at 30 September 2026. It also carries no debt.
Q3: When is the McPhillamys FID targeted?
A3: FID is targeted for H1 CY28. The project has a 1.9Moz Reserve and ~10 years of planned production.
Q4: What dividend did Regis declare for FY26?
A4: Total FY26 dividends were 35cps, a 6.5% yield. The 20c final dividend cost $152M.
Disclaimer:
This article summarises Regis Resources’ 2 November 2026 analyst presentation and is general information only. It is not financial advice. Production guidance, costs and project timelines are forward-looking. They may shift with gold prices, weather, approvals and operating conditions. Resource and Reserve figures follow JORC 2012. Readers should check official ASX announcements and seek independent advice before making investment decisions.
Elizabeth Jones is a finance and mining content specialist with over 10 years of experience creating clear, SEO-driven content across fintech, investing, banking, insurance, cryptocurrency, and resource markets. She transforms complex financial data and industry trends into engaging, reader-focused articles that improve understanding and audience engagement.