PLS Group’s heaviest quarter ever resulted in a downturn in revenues. Lithium miner ASX-listed Pilbara Minerals published its quarterly presentation on 28 October 2026 containing September quarter FY27 results. Spodumene concentrate production jumped to a record 267.6kt, an increase of 25% for the June quarter. Group revenues declined by 24% to A$563M, however.
The primary reason is cost, but also the timing. The average estimated realised price on an SC5.2 basis was US$1,809/t, which was 14% lower than the average. The company attributed the decrease in sales volume to shipment timing, and the slump was 11% to 223.6kt. A positive currency trend helped to cushion some of the impact. At the end of the quarter, cash was A$2,217M.
PLS owns 100% of its lithium assets in Australia and Brazil. It also has an interest of 18% in a lithium hydroxide plant in South Korea. The spread provides management with flexibility as markets turn.
Pilbara Minerals Lithium Production Hits a Record
The vast majority of the tonnes were from Pilgangoora, in Western Australia. The total material mined rose to 11.5 million tonnes, of which 1.5 million tonnes was ore. The recovery of lithium was approximately 75% due to the strong ore sorting. The restart of the Ngungaju project also remained on track. The plant re-opened at the end of October.
Costs moved the right way too. Unit operating cost (FOB) fell 12% to A$539/t, or US$381/t. The company pointed to operational efficiencies and a larger volume of capitalised waste. Cash margin from operations dropped 32% to A$392M. Capex jumped 50% to A$185M, and a A$161M final FY26 dividend went out the door.
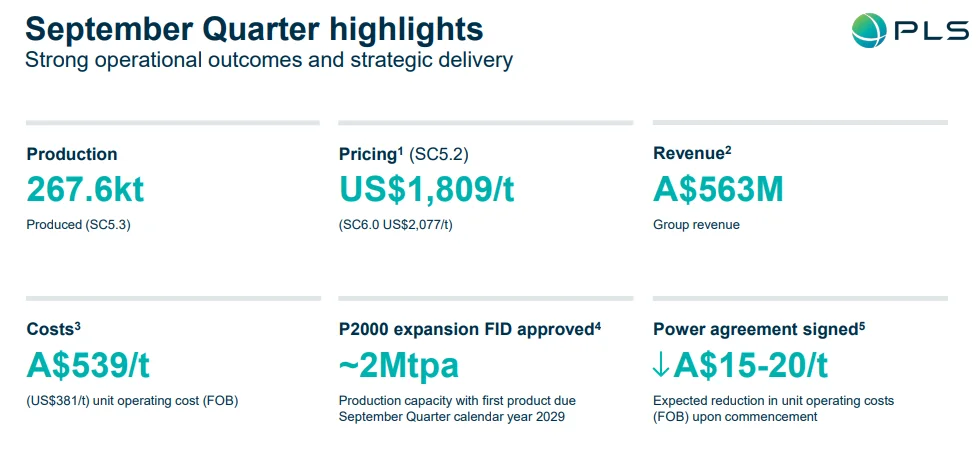
Unit operating costs (FOB) fell 12% to A$539/t during the quarter. [PLS Group]
The PLS Group FY27 Outlook at a Glance
Guidance for the year is largely untouched. Only capex moved, to fold in the new power agreement. The updated ranges are:
- Production volume of 1,030 – 1,100kt, assuming an average product grade of about SC5.2.
- Unit operating cost (FOB) of A$575 – 625/t.
- Total capex of A$1,130 – 1,195M.
- Sustaining capital of A$85 – 100M, mine development of A$250 – 280M, and infrastructure and projects of A$110 – 130M.
P2000 growth capex of A$500M, plus A$185M for the access road, permanent village, mine services facility and power agreement.
How the PLS Group Lithium Expansion Takes Shape
On 16 October 2026, the board approved the P2000 final investment decision. The project lifts Pilgangoora capacity to about 2Mtpa and adds a third major processing facility, the Jimmagunya plant. The main details are:
- Cost and return: Project capex is about A$1.9B, against an incremental net present value of A$2.7B at an 8% real, post-tax discount rate.
- Timing: First production is due in the September Quarter of calendar year 2029, followed by a ramp-up of about six months.
- Unit costs: Average unit operating costs (FOB, real) should sit near A$600/t over the first 10 years.
- Reserves: The Ore Reserve rose 31% in contained lithia, and it underpins the production targets.
- Power: A 20-year agreement with Fortescue supplies a minimum of 325 GWh p.a. PLS expects it to trim unit costs by A$15-20/t.
- Infrastructure: A$600 – 650M goes to a sealed access road, a 1,200-bed village and a mine services facility.
Balance Sheet Strength and Market Risks
Funding looks comfortable. After quarter-end, PLS closed a US$700M 8.00% Senior Unsecured Notes offering. Pro forma cash rises to A$3,209M, and pro forma liquidity reaches A$3,709M.
Across both notes, the weighted average cost of funds is 7.48% p.a. Weighted average debt maturity stretches to 5.3 years. Net cash was A$1,277M at 30 September.
Pricing is the real risk. September quarter revenue includes negative provisional pricing adjustments of A$69M. By 26 October 2026, the estimate had grown to A$88M.
The estimated realised price had also eased to US$1,754/t. Longer term, Benchmark Mineral Intelligence sees lithium demand tripling by 2040. It also warns the CY27 deficit could rise from about 100kt to about 500kt LCE.
What Investors Should Watch Next
Several milestones will test the strategy over the coming quarters. Updates will land on the official page. The dates and figures to track are:
- Mid-Stream Demonstration Plant: first product is now expected in the December Quarter 2026.
- Colina Project in Brazil: study outcomes are due in the December Quarter 2027.
- South Korean chemicals plant: 3,558 t of lithium hydroxide produced, about 98% battery grade.
- Safety: a total recordable injury frequency rate of 2.36.
Also Read: Blockmate Ventures Acquires Initial NVIDIA B200 AI Compute Node
FAQs
Q1: What did PLS Group report for the September quarter FY27?
A1: Production reached a record 267.6kt, up 25%. Revenue fell 24% to A$563M on weaker prices.
Q2: What is the P2000 expansion?
A2: It lifts Pilgangoora capacity to about 2Mtpa for about A$1.9B. First production is due in the September Quarter of calendar year 2029.
Q3: How strong is the PLS balance sheet?
A3: Cash was A$2,217M at 30 September. The US$700M notes lift pro forma cash to A$3,209M.
Q4: What is the FY27 guidance?
A4: Production is guided at 1,030 – 1,100kt. Unit operating cost (FOB) is A$575 – 625/t.
Disclaimer:
This article summarises PLS Group’s September quarter FY27 presentation and is general information only. It is not financial product advice or a recommendation on ASX: PLS shares. Guidance, pricing estimates and the P2000 timeline may change. Lithium equities are volatile and speculative. Do your own research. Check the original ASX releases and consult a licensed adviser before investing.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.