Emerald Resources NL (ASX: EMR) lodged its September 2026 quarterly report on 30 October. Gold came in lighter. Emerald Resources’ gold production fell to 20.3Koz at Okvau, down from 27.1Koz in June.
Costs moved the other way. All-in sustaining costs (AISC) rose to US$1,210/oz from US$818/oz. Guidance didn’t budge, though. This ASX EMR production update covers what happened, why, and what’s next, using the company’s quarterly report.
Emerald Resources Quarterly Results: What Actually Happened
Okvau produced 20,280oz in the quarter, with 23,003oz poured. Sales hit 23.8Koz at an average US$4,255/oz, which brought in US$101.4M. Pre-tax operating cash flow was A$112.4M (US$79.4M). June’s figure was A$127.3M (US$90.3M). Less gold, then, but plenty of cash.
The plant wasn’t the problem. Availability sat at 98%, and 596,852 dry tonnes went through the mill. That’s about 18% above the 500,000 t nameplate. Recovery held at 86%. Grade was the culprit at 1.23g/t, down from 1.75g/t. Ore mined also slipped to 478Kt from 619Kt.
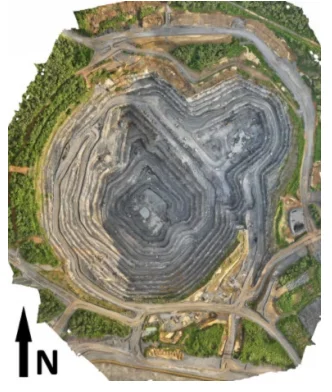
The Okvau open pit in September 2026, where Stages 6 and 9 supplied ore.
Why Costs Jumped So Quickly
Fewer ounces had to carry a similar cost base. Total cash costs were US$20.3M, against US$17.7M in June. The stripping ratio climbed to 11.23 from 7.74. In plain terms, miners moved more waste for every tonne of ore.
Royalties took US$3.0M, and all-in sustaining costs totalled US$24.5M. That leaves AISC well above the FY27 range of US$980/oz – US$1,080/oz. Management still held production guidance at 100Koz – 115Koz.
A stockpile of circa 1.29g/t (414Kt) sits ready for the mill. Another 3.71Mt of low-grade ore is stockpiled at 0.66g/t. Since September 2021, Okvau has produced 529,880oz at an average AISC of US$897/oz.
Where the Cash Sits
The balance sheet is the steadier part of this report. Here’s the breakdown:
- Cash, bullion and listed investments totalled A$540.9M (US$377.4M) at 30 September 2026.
- Cash alone was A$483.0M (US$337.0M), with bullion at A$29.6M (US$20.6M).
- Listed investments added A$28.3M (US$19.8M).
- A US$200M Corporate Acquisition Facility mandate was signed with Sprott and Macquarie.
- The facility can scale to US$400M, with a five-year term anda 36-month availability period.
- Dingo Range and Memot are funded from existing cash of approximately A$500M.
The new facility is meant for buying projects, not building these two. It remains subject to due diligence and final documents. Emerald also holds 19% of Manda Resources. It plans to keep about 19.9% after Manda’s proposed ASX listing. Total growth spending for the quarter was $41.8M.
How Dingo Range and Memot Are Tracking
Two projects carry the growth story. Their latest status looks like this:
- Dingo Range is fully permitted, with orders placed for the SAG mill, crushing circuit and CIL tanks.
- MACA Mining is the preferred contractor, with fleet mobilisation scheduled for December 2026.
- The Dingo Range resource stands at 40.9Mt @ 1.1g/t Au for 1.41Moz.
- Memot is fully permitted, and its resource is 45.0Mt @ 1.2g/t Au for 1.7Moz.
- Okvau drilling returned 20m @ 14.97g/t Au from 523m, including 5m @ 45.93g/t Au from 527m.
- Boundary returned 2.1m @ 101.02g/t Au from 405m.
Dingo Range now awaits its maiden ore reserve and Definitive Feasibility Study. The study is nearing completion. At Memot, resettlement programs are significantly advanced. Infill drilling there returned 6m @ 6.31g/t Au from 28m. Snuol added 1.6m @ 25.03g/t Au from 158.8m, and those prospects are being assessed as feed for the proposed Memot plant.
What to Watch Before the Next Update
Several things could shape the December quarter. Keep an eye on these:
- Maiden ore reserves and feasibility studies for Dingo Range and Memot, both due in the near term.
- Okvau head grade, which drives both ounces and unit costs.
- The Stage 9 cutback, after US$11.1M of capital spend ahead of future underground work.
- Acquisitions, which support Emerald’s goal of 600koz to 800koz a year.
Is output under pressure? For now, yes. Grade and stripping did the damage. But guidance held, cash is deep, and both projects are funded. That reads as manageable, not alarming. More detail sits in the ASX announcements for EMR.
Also Read: Liontown’s September Quarter: A Lithium Turning Point?
FAQs
Q1: Why did Emerald’s gold production fall in the September quarter?
A1: Ore grade slipped to 1.23g/t from 1.75g/t in June. Output followed, dropping to 20.3Koz from 27.1Koz.
Q2: Has Emerald changed its FY27 guidance?
A2: No. It still expects 100Koz – 115Koz of gold at AISC of US1,080/oz.
Q3: How much money does Emerald have in the bank?
A3: Cash, bullion and listed investments add up to A377.4M). Cash on its own is A337.0M).
Q4: When will mining equipment arrive at Dingo Range?
A4: The mining fleet is scheduled to reach site in December 2026. The project holds a resource of 40.9Mt @ 1.1g/t Au for 1.41Moz.
Disclaimer:
This piece is based on Emerald Resources NL’s September 2026 quarterly report. It is general information only. It isn’t financial, investment or mining advice. Gold prices, ore grades, costs and timelines can shift fast, and forward-looking statements are never guaranteed. Check the original ASX announcements carefully. Consider your own situation and talk to a licensed financial adviser before you invest.
Elizabeth Jones is a finance and mining content specialist with over 10 years of experience creating clear, SEO-driven content across fintech, investing, banking, insurance, cryptocurrency, and resource markets. She transforms complex financial data and industry trends into engaging, reader-focused articles that improve understanding and audience engagement.