The Westfield owner filed its operating update on Wednesday 4 November. Most of it is a tidy scorecard, with footfall, sales and leasing all pointing up.
Then comes a short section on David Jones, added because of media reports about the department store and its owner, Anchorage Capital Partners.
The Australian Financial Review reported that David Jones directors were expected to appoint McGrathNicol as voluntary administrators on Thursday, after landlord talks broke down. Scentre’s filing confirms none of that. It just answers the question landlords are being asked: how much is at stake?
The Scentre Group David Jones exposure comes down to a few numbers
David Jones trades from 17 Westfield centres. Scentre’s share of its 2026 gross rent is $45 million.
That works out at $352 a square metre. The average across the whole portfolio is $942, so the department store pays just over a third of what a typical tenant does.
Table 1: Scentre’s David Jones exposure, as disclosed on 4 November 2026
| Item | Figure |
|---|---|
| Westfield centres with David Jones | 17 |
| Scentre share of 2026 gross rent | $45 million |
| Rent per square metre | $352 (portfolio average $942) |
| Share of gross rent | About 1.8% |
| Share of annualised FFO | About 3.6% |
| Bank guarantees, Scentre share | About $30 million (eight months of rent) |
Source: Scentre Group ASX announcement, 4 November 2026
The stores make up about 1.8% of gross rent but about 3.6% of annualised FFO. Why double?
Gross rent is the top line. FFO is what survives interest and running costs. Lose a tenant and the rent goes, but most of the cost of owning the building stays.
Back of the envelope, 3.6% of a 23.79 cent FFO is roughly 0.86 cents per security. That is a rough sum from the filing’s percentages, not a Scentre figure.
There is an oddity in the fine print. $45 million at $352 a square metre implies about 128,000 square metres, yet the filing says 200,000.
The likely answer is that the floor area covers the whole building while the rent is only Scentre’s share. The announcement does not say, so treat that as a guess.
Eight months of bank guarantees sit behind the rent
The most useful line in the filing is a short one. “David Jones paid all rent up to 30 September 2026.”
Behind that sits a pile of bank guarantees. David Jones lodged $45 million across the Westfield Australia and New Zealand portfolio, and Scentre’s slice is about $30 million.
Scentre says the guarantees were a condition of approving Anchorage’s 2023 purchase. That condition looks a lot smarter today than it did then.
The sums are simple. $45 million a year is $3.75 million a month, so eight months of cover from 1 October runs to the end of May 2027.
The filing is silent on how fast cash arrives if a call is needed.
There is also a paperwork problem. ASIC told AAP that David Jones had not filed its 2025/26 accounts, missing an end-of-October deadline. No fresh accounts means outsiders are guessing at the balance sheet.
The 2026 FFO target holds, and the condition attached finally matters
Scentre reaffirmed FFO of at least 23.79 cents per security for 2026, up at least 4.25%. Distributions are pencilled in at 18.473 cents.
The guidance carries the usual condition about no material change in conditions. This time that condition is doing real work.
Rent is paid to September and guarantees cover about eight months beyond. A David Jones collapse this month should barely dent 2026.
Management also would not repeat a target days before a possible administration unless the sums were done. That is a read, not a fact.
The rest of the update backs the tone:
- Occupancy is 99.8%, the highest in more than a decade.
- Specialty sales rose 4.6% in the three months to 30 September.
- Leasing teams closed 2,085 deals at specialty spreads of +3.7%.
Cash is not tight either. Liquidity of $3.4 billion covers maturities until the second half of 2029, and the October US$750 million bond priced 141 basis points over BBSW.
The Mt Gravatt sale to Australian Retirement Trust has also settled, at $882.5 million for a 50% stake.
The pain was already visible in the sales table. Department store sales fell 3.7% in the September quarter while specialties grew 4.6%.
The real test in 2027 is who fills the boxes
The risk is not this year’s FFO. It is next year, when big boxes could go dark.
Tuggerah offers a template. Scentre is spending $20 million to turn the old David Jones space into new tenancies.
JD Sports and rebel are open, and visitation is up 6.2% in the eight weeks since. TimeZone follows in Q2 2027.
On paper, backfilling looks sweet. Swap $352 rent for something nearer $942 and the maths glows.
In practice, large boxes rarely re-let at the portfolio average, and empty months cost money.
Reports say McGrathNicol has been in touch with potential bidders, including interests linked to Brett Blundy and Larry Kestelman. A buyer for part of the network would soften the blow. A broad closure list would not.
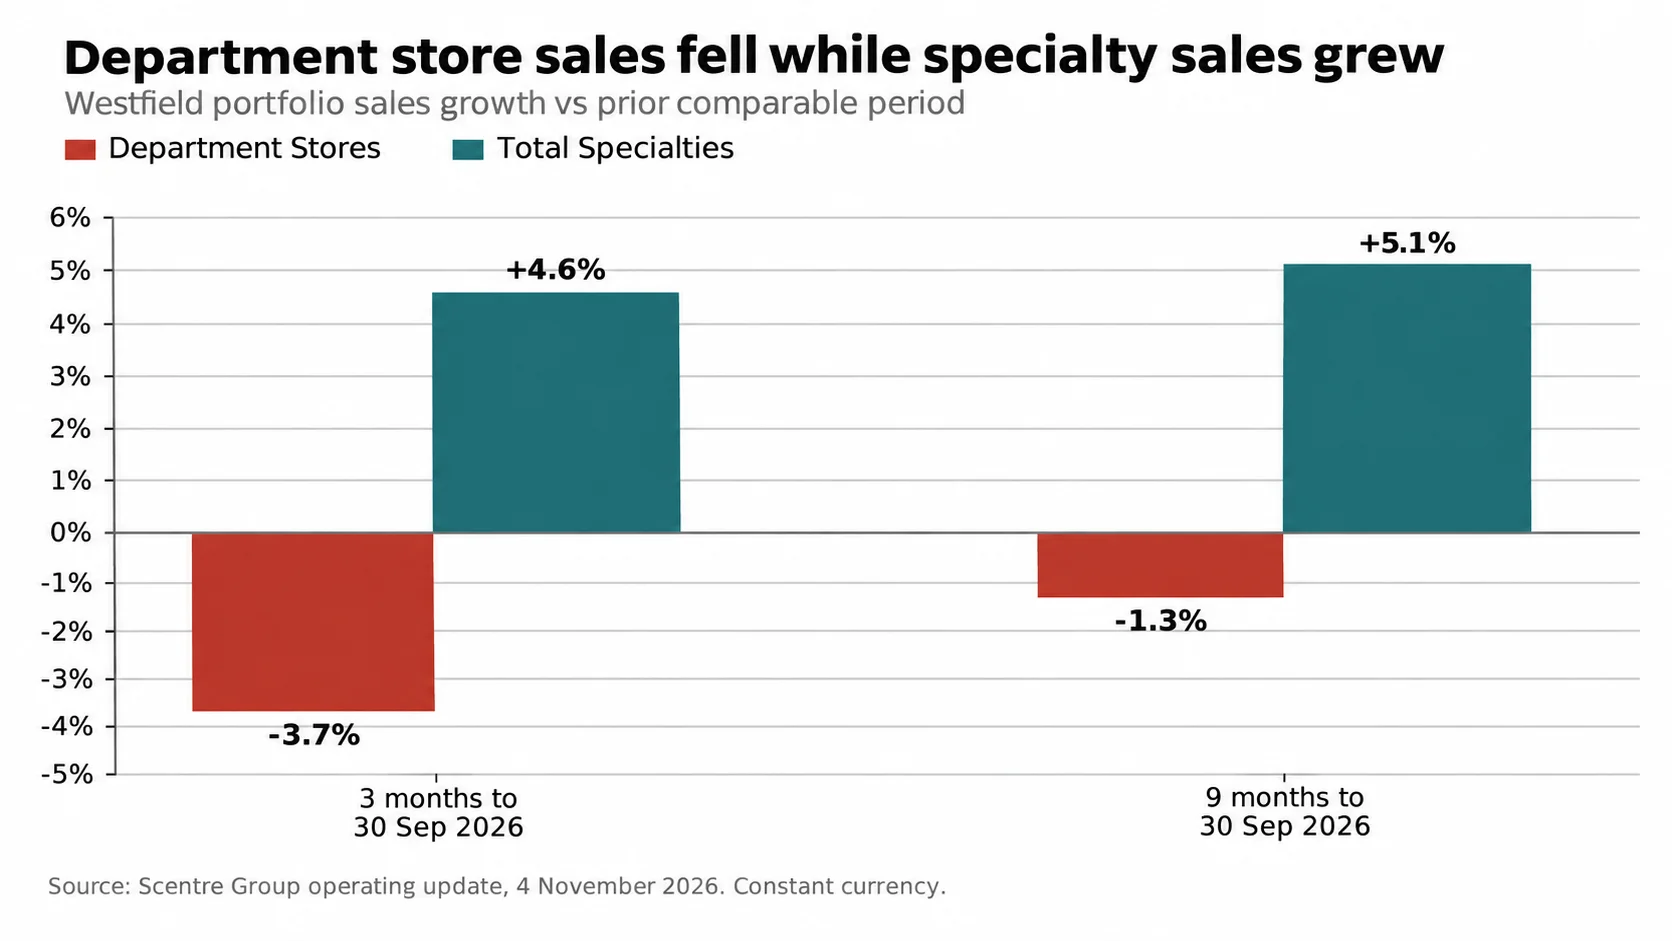
Department store sales fell while specialty sales grew across Westfield centres in 2026.
Scentre is not the only landlord. The same reports say Vicinity, GPT and Stockland host other David Jones stores. Scentre has put its numbers out, and the others will probably be asked for theirs.
A year ago, the November update said the final stage of an upgraded David Jones would open that month. Department store space ages fast.
Scentre has other big moves in play, including its talks on a Westfield Sydney joint venture.
The 3.6% is a number Scentre can carry. The better question is how many of these 17 boxes reopen under a new name by this time next year.
Also Read: Ingenia Takeover Hits a Tie as AVID Matches Warburg
FAQs
Q: How much rent does David Jones pay Scentre Group?
A: About $45 million in 2026, Scentre’s share, across 17 Westfield centres.
Q: What share of FFO is that?
A: About 3.6% on an annualised basis.
Q: Is the SCG ASX FFO target still on?
A: Yes, at least 23.79 cents per security for 2026, subject to no material change in conditions.
Q: Has David Jones paid its rent?
A: Yes, up to 30 September 2026.
Q: Is David Jones in administration?
A: Scentre’s filing does not say so. Media reports point to an appointment as soon as 5 November.
Disclaimer:
This article is general information only and is not financial advice. It does not consider your objectives, financial situation or needs. Consider speaking with a licensed adviser before making investment decisions
Elizabeth Jones is a finance and mining content specialist with over 10 years of experience creating clear, SEO-driven content across fintech, investing, banking, insurance, cryptocurrency, and resource markets. She transforms complex financial data and industry trends into engaging, reader-focused articles that improve understanding and audience engagement.