The Ingenia takeover bid has gained another 10 cents. The price is the least interesting part.
On Friday 6 November, Ingenia told the ASX that Warburg Pincus now offers $5.55 cash per stapled security. That is one unit bundling shares and trust units. Discovery Parks Holdings and LDR Capital stand beside Warburg as co-investors.
Warburg also says shareholders keep the half-year distribution, worth up to 5c. That lifts the total to as much as $5.60, against $5.50 from rival AVID Property Group.
Counting this one, Warburg has named five prices. It opened at $4.75, then went to $5.05, $5.25, $5.45 and now $5.55.
Warburg is a New York private equity firm. AVID is a Sydney developer backed by US fund manager Proprium Capital Partners.
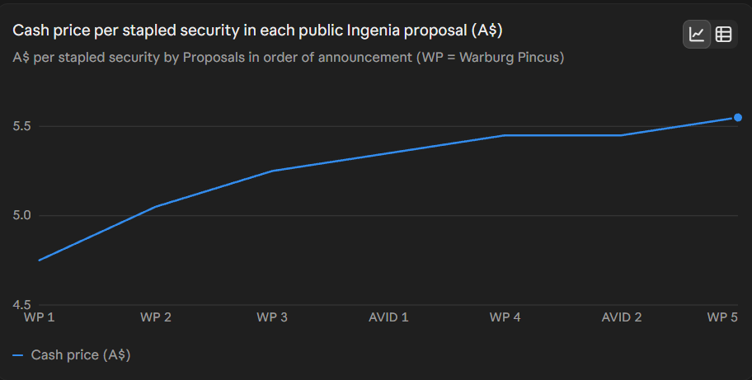
Cash price per stapled security in each public proposal for Ingenia, in order of announcement. Excludes the permitted distribution of up to 5c attached to the latest offers. [ASX]
The Ingenia takeover bid is turning into a fight over process
AVID holds a matching right. Ingenia cannot switch to Warburg until AVID gets a chance to match.
That right has already bitten once. AVID matched Warburg’s $5.45 on 2 November, and Warburg lost its data room access again.
Warburg tried a fix on 3 November. It kept the price and changed the rules, and the board said no the next day because the offer was no better.
The new bid brings both: 10c more, plus a rule change. If a rival matches, the other bidder would keep data room access for four days, and Warburg wants exclusivity until 14 December.
Without that clause, every Warburg raise works like a free preview for AVID. Warburg shows its number, AVID copies it, and Warburg is shut out again.
This desk reads the clause as a quiet admission. Price alone has not beaten the matching right, so Warburg is trying to change the game around it.
The reported structure adds a twist. Ingenia would be split three ways: Warburg keeps land lease communities, Discovery Parks takes the holiday parks, and LDR Capital takes Ingenia Gardens.
Warburg also argues that Discovery Parks would overlap less with Ingenia’s holiday parks than AVID’s plan to hand them to Tasman Holiday Parks, as reported by Real Estate Source. That reads like a message for the competition regulator.
| Warburg Pincus consortium | AVID | |
| Cash per security | $5.55 | $5.45 |
| Permitted distribution | Up to 5c | Up to 5c |
| Total | Up to $5.60 | Up to $5.50 |
| Holiday parks | Discovery Parks | Tasman Holiday Parks or nominee |
| Gardens | LDR Capital | Not separately specified |
| Peet deal | Must be terminated | Must be terminated |
| Status | Non-binding, board met 6 Nov | Non-binding, process deed in place |
Ten cents is small change next to a $3.2 billion prize
Real Estate Source puts the equity value at about $2.3 billion, or $3.2 billion once debt is counted. Each 10c step costs a bidder roughly $40 million.
That is just over 1% of the full price. Cheap, by deal standards.
Now compare the Peet exit fee. Dropping Peet for a better bid triggers a $10 million reverse break fee, so one 10c step costs four times that.
Money is unlikely to stop either bidder soon. The brakes sit elsewhere. Foreign Investment Review Board and Australian Competition and Consumer Commission approval, binding debt and investment committee sign-off all remain open, per the ASX release.
Peet is the knot neither bidder has cut
Both bidders want Ingenia to drop its planned Peet purchase, a deal worth close to $1 billion. The board still backs it and says it is working to complete it.
Peet shareholders vote on 7 December. Peet’s board unanimously recommends the deal unless a superior offer appears, and independent expert Kroll found it fair and reasonable on that basis.
The calendar looks tight. A footnote in the release says Ingenia’s right to exit Peet ends at 8am on the second court date, which Mingtiandi puts in early December. Warburg wants exclusivity until 14 December.
Something has to give. Either the dates move, or the board must decide on Peet before a binding Warburg deal is signed.
The Weekly Source reported that Peet also moved on Friday. It signed a deal with Brown-Neaves interests over Flagstone City in Queensland, where they would take 49.9% on an agreed $615 million inventory value if Ingenia completes the purchase.
Ingenia says Peet could add 5,000 to 7,000 potential land lease sites. Next to its current 96 communities and development sites, that is a lot of runway.
Shareholders are being paid to wait, and AVID moves next
Nothing here is binding. Ingenia says securityholders need not act.
The shares closed at $5.20 on Thursday, 40c below the top of Warburg’s range. That 7.7% gap says the market sees a real chance, not a sure thing.
They are also up about 41% from the $3.69 close on 28 August, the last close before Warburg’s first approach went public. Warburg’s $5.55 sits 50.4% above that level.
The board was due to meet on Friday to decide whether its duty to shareholders lets it open the door to Warburg and start AVID’s matching window.
Last round, AVID used its full window and matched on the final day, Sunday 1 November. Warburg wants exclusive access by Tuesday 10 November.
Neither bidder has shown a ceiling in this Ingenia takeover contest. Another 10c invites another 10c. If Warburg wants to end the loop, one bigger step, or a term AVID cannot copy, would do more than another small bump.
Also Read: NextDC Stake Purchase Raises a Bigger Takeover Question
FAQs
Q: What is Warburg offering?
A: $5.55 cash per security, plus a permitted distribution of up to 5c.
Q: What is AVID offering?
A: $5.45 cash, plus the same distribution of up to 5c.
Q: Is the offer binding?
A: No. It is non-binding and conditional.
Q: Do shareholders need to act?
A: Not now, according to Ingenia.
Q: What happens to Peet?
A: Both bidders want it dropped, and Peet holders vote on 7 December.
Disclaimer: This article is general information only and not financial advice. It does not consider anyone’s objectives, financial situation or needs. Speak to a licensed adviser before making investment decisions. Figures come from company filings and media reports as at 6 November 2026.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.