Perseus Mining has reported a softer September quarter. The ASX/TSX-listed miner mined 92,551 oz of gold, which dipped by 16,462 oz. On 27 October 2026, Perseus Mining’s Q1 FY27 results were released. Move guidance was not applied.
Although prices were down, costs were up. The average sale price was US$3,881/oz, down US$205/oz. All-in site cost (AISC) rose US$94/oz to US$2,035/oz. This compressed margin; the cash price stood at US$1,846/oz, which was US$299/oz lower than the previous day.
Notional cash flow came in at US$171M, down US$45M. Net cash and bullion sits at US$900M, down US$134M. The company carries no debt, and US$400M of facilities remain undrawn. Safety looked steadier, with a Group TRIFR of 1.01.
Why Margins Tightened Over the Quarter
Three things squeezed the result, and the quarterly figures show all of them:
- Lower output: Group production fell 16,462 oz, and Sissingué dropped 29% in Q4.
- Higher costs: AISC rose US$94/oz, and Q1 carries US$4.6 million of excess waste stripping.
- Softer prices: The average sale price slid from US$205/oz to US$3,881/oz.
Cash still did plenty of work. Operating cash flow was US$187M. Capital and exploration took US$160M, and working capital and corporate items used US$67M. Liquidity totals US$1,300M, and listed securities add US$338M.
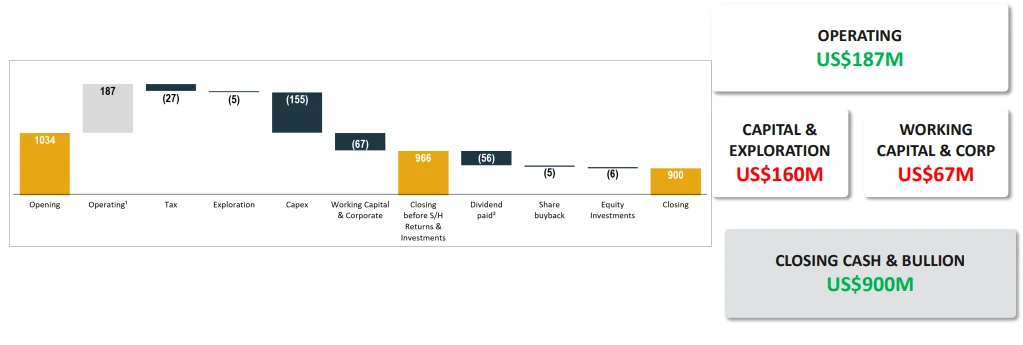
Operating cash flow of US$187M covered capital and exploration spending. [Perseus Mining]
Where Yaouré, Edikan and Sissingué Landed
The three producing mines had very different quarters. Here is how they compare:
- Yaouré (Côte d’Ivoire): Output was 36.6koz, down 6% on Q4, at an AISC of US$2,393/oz. CMA Underground reached commercial production on 1 July 2026. Notional cash flow rose 6% to US$53M.
- Edikan (Ghana): Output was 35.8koz, down 15% on Q4. AISC fell 11% to US$1,738/oz. Notional cash flow was US$80M, down 20%.
- Sissingué (Côte d’Ivoire): Output was 20.0koz, down 29% on Q4. AISC climbed 23% to US$1,913/oz. Notional cash flow was US$38M, down 42%.
Sales add some colour. Yaouré sold 40,009 oz at a weighted average of US$3,845/oz. Edikan sold 35,995 oz at US$3,968/oz, while its Fetish and Esuajah North cutbacks progressed. Sissingué sold 23,657 oz at US$3,811/oz. High-grade ore from the Antoinette pit at Bagoé helped there.
Yaouré’s production is weighted to the second half. The open pit reaches higher-grade ore, and underground output rises.
How Nyanzaga Could Change the Picture
Nyanzaga in Tanzania is the next big step. Construction progress was 88% as of September 2026. Total construction costs incurred were US$408M, or 84% of the total. Pre-production costs incurred came to US$33M. First gold is still on track for January 2027.
The numbers behind the project are sizeable. The Mineral Resource is 4,715 koz at 1.33 g/t. The Ore Reserve is 4,109 koz at 1.34 g/t. Perseus sees a 16-year life, from FY28 to FY41, at more than 200koz a year. Average AISC is pegged at US$1,600–US$1,700/oz. Those estimates trace back to the 26 August 2026 resource update.
FY27 guidance includes about 55,000 oz from Nyanzaga. Commercial production is planned for Q4 FY27. Further guidance is due in Q3 FY27.
When Shareholders Get Paid
Perseus is also leaning on capital returns. The main points are:
- Distributions: A$667M has gone back to shareholders since FY24.
- Special payout: About A$100M is proposed, funded by the sale of Sudan.
- Buyback: The FY27 buyback is approved and upsized to A$350M.
- Host countries: Economic contribution reached US$407m, including US$109.3M in taxes and royalties.
Group FY27 guidance stays at 420,000–480,000 oz. AISC is guided at US$1,835–US$2,070/oz. That assumes gold at US$4,000/oz and excludes Nyanzaga. Investors will watch the second half closely.
Also Read: ASX GGP: How Telfer Supports Greatland’s Expansion
Frequently Asked Questions
Q1: How much gold did Perseus Mining produce in the September quarter?
A1: The Group produced 92,551 oz, down 16,462 oz. Gold sold at an average of US$3,881/oz.
Q2: What is Perseus Mining’s FY27 production guidance?
A2: Group guidance is 420,000–480,000 oz at an AISC of US$1,835–US$2,070/oz. It remains unchanged.
Q3: When will Nyanzaga pour its first gold?
A3: First gold is targeted for January 2027, with construction 88% complete. Commercial production is planned for Q4 FY27.
Q4: How much is Perseus returning to shareholders?
A4: A$667M has been returned since FY24. An A$350M buyback and a ~A$100M special distribution add to that.
Disclaimer:
This article summarises Perseus Mining’s September quarter presentation dated 27 October 2026. It is general information only and not financial advice. Forward-looking items depend on gold prices and operating conditions. These include FY27 guidance, Nyanzaga’s first gold date and the proposed A$100M special distribution. Readers should check ASX and TSX filings and speak with a licensed adviser before investing.
Elizabeth Jones is a finance and mining content specialist with over 10 years of experience creating clear, SEO-driven content across fintech, investing, banking, insurance, cryptocurrency, and resource markets. She transforms complex financial data and industry trends into engaging, reader-focused articles that improve understanding and audience engagement.