The Daiichi Life takeover approach for Challenger (ASX: CGF) reached the board after the close on Friday 16 October. By Monday morning it was all anyone on the ASX wanted to talk about.
TAL Daiichi Life Australia, the local arm of the Japanese insurer, already holds about 20.4%. It wants the other 79.5% through a scheme of arrangement.
Bids this size rarely come from nowhere, and this one did not.
The A$11.80 non-binding proposal carries a modest premium
The headline number sounds fat. It values the whole company at about A$7.94 billion, and the slice TAL Daiichi Life does not own at roughly A$6.3 billion.
The fine print is where it gets interesting:
- A$11.80 a share through a scheme of arrangement
- 7% above the one-month VWAP of A$10.03, per Challenger’s own release
- 8% above Friday’s A$9.85 close, per Reuters
- Conditions include due diligence, a scheme implementation agreement, regulatory approvals and a board recommendation
Two premiums, two stories. Challenger quoted the smaller one, which reads like a board leaving itself room to ask for more.
Control premiums on Australian deals are often cited nearer 30%. At 17.7%, there is space to push.
Even the bidder is hedging. Daiichi Life told its own market that no decision has been made on going binding.
Shares closed five cents short of the offer
Challenger finished Monday at A$11.75, up 19.3% on Friday. It touched A$11.05 along the way, and more than 8.5 million shares changed hands.
That is the highest the stock has been since October 2018.
Now look at the gap. Five cents on A$11.75 is about 0.4%.
A gap that thin on a proposal nobody has agreed to says one of two things. Either the market thinks the deal is nearly done, or it is betting on a bigger number.
The first reading is hard to defend with a board that has not opened its books and a list of conditions still unticked. The second looks likelier.
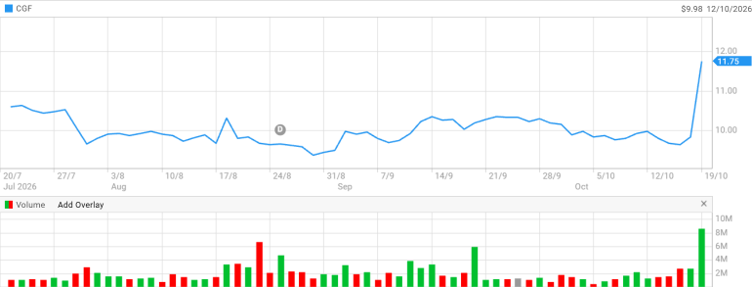
CGF share price performance [ASX]
TAL Daiichi Life has been building the runway for 18 months
In April 2025, the Japanese group bought MS&AD’s 15.1% stake for 80 billion yen. Top-ups followed, and the holding now sits near 20.4%.
On a rough conversion, that first parcel cost close to A$8.50 a share. A$11.80 is about 40% above it.
A fifth of the register is a handy seat to sit in. A rival bidder would have to climb over it.
If the board says no, Australian rules generally let a holder past 19% add 3 percentage points every six months without a bid. Daiichi can wait.
The business logic is easy to see. TAL writes life insurance, so it carries the risk that people die early. Challenger writes annuities, so it carries the risk that people live long.
Under one roof, those two risks partly cancel out. Capital models like that.
The release names no regulator, only “various regulatory bodies”. APRA is the obvious first stop, since Challenger runs an APRA-regulated life company.
A strong quarter landed the same day, but not all of it is steady
Challenger also released its first quarter update on Monday. Total sales hit A$4.4 billion, up 52%, and assets under management rose 5% to A$31.9 billion.
Open the quarterly table and one line jumps out. Institutional fixed term sales above one year came in at A$1.32 billion. The quarter before, they were A$23 million.
Part of that is the first A$750 million note under the new CABN program. Money that arrives in lumps can leave just as quickly.
Lifetime sales, the product most Australians picture when they hear “Challenger”, slipped 2% to A$314 million.
Fidante tells a softer story. Its funds under management fell 5% to A$85 billion, with A$4.6 billion walking out of equity strategies.
That arm is heading into the Channel Capital merger, where Challenger will keep 45%. Daiichi would be buying the annuity engine, not the funds business.
| A$ million | Q1 FY27 | Q4 FY26 | Q1 FY26 |
| Total sales | 4,375 | 2,740 | 2,869 |
| Total annuity sales | 2,823 | 1,287 | 1,645 |
| Institutional fixed term sales, over 1 year | 1,316 | 23 | 28 |
| Lifetime sales | 314 | 353 | 320 |
| Fidante FUM | 85,047 | 89,528 | 91,413 |
Next comes the board’s call on whether to open the books. If it does, a higher price is the likely cost of entry.
Anyone tracking ASX takeover bids will know the pattern. A first offer is rarely the last one. The wider ASX financial results season will show how many boards hold out.
Also Read: WiseTech Global: ASIC Closes Two Probes, Not the Story
FAQs
Q: Has Challenger accepted the Daiichi Life offer?
A: No. The board is still considering it.
Q: Is the A$11.80 proposal binding?
A: No. It is non-binding and conditional.
Q: Do shareholders need to do anything?
A: No action is needed for now.
Q: How much of Challenger does TAL Daiichi Life own?
A: About 20.4%.
Q: Why did the shares stop below A$11.80?
A: Doubt over conditions and timing keeps the price under the offer.
Disclaimer: This article is general information only and is not financial advice. It does not consider anyone’s objectives, financial situation or needs. Takeover proposals can change or lapse. Readers should do their own research and speak to a licensed adviser before making investment decisions.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.