New Hope and Malabar outlined their proposed combination on 19 October 2026. Malabar shareholders would receive 0.500 New Hope shares for each Malabar share, subject to dividend adjustments set out in the transaction documents.
The New Hope Malabar merger places a fully diluted equity value of approximately A$1.8 billion on Malabar on a 100% basis.
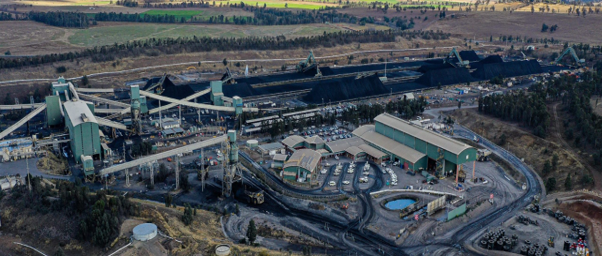
Figure 1: Coal-handling infrastructure at Bengalla Mine in New South Wales, where New Hope holds an 80% interest. Archive photograph. Credit: TVOS Contractors.
What Would Malabar Shareholders Receive?
The proposed exchange ratio implies A$2.92 per Malabar share at the New Hope share price used in the presentation.
That value will move with New Hope’s share price. It is not a fixed cash payment.
New Hope’s existing shareholders would own approximately 79% of the combined company. Malabar shareholders other than New Hope would hold about 21%.
| Transaction detail | Proposed terms |
| Consideration | 0.500 New Hope shares per Malabar share |
| Implied value at announcement | A$2.92 per Malabar share |
| Malabar equity value, 100% fully diluted basis | Approximately A$1.8 billion |
| Existing New Hope shareholder ownership | Approximately 79% |
| Other Malabar shareholder ownership | Approximately 21% |
| Target completion | February–March 2027 |
New Hope already holds approximately 25.97% of Malabar. Its existing Malabar shares will not be voted at the scheme meeting.
Both boards support the proposal. Malabar’s recommendation remains subject to no superior proposal emerging and an independent expert continuing to find the scheme in the interests of shareholders other than New Hope.
Maxwell Adds an Underground Mine to the Portfolio
Bengalla and New Acland are open-cut operations. Maxwell would add underground mining, with high-energy thermal coal and the ability to produce semi-soft coking coal.
The presentation sets out the following longer-term production targets.
| Operation | Combined group interest | Long-term saleable production target |
| Bengalla | 80% | 8.4Mtpa attributable |
| New Acland | 100% | 5.0Mtpa |
| Maxwell | 100% | 5.5Mtpa |
These are targeted steady-state figures beyond the next five years, rather than current annual output.
Maxwell’s total comprises about 0.5Mtpa from bord-and-pillar operations and 5.0Mtpa from longwall mining. Its approved operating life exceeds 20 years.
For New Hope coal assets, the addition would broaden the production base while keeping the business concentrated in Australian coal.
Colitco’s earlier coverage of New Hope’s operating performance provides background on Bengalla’s contribution to the group.
Maxwell’s Ramp-Up Is the Near-Term Operating Test
Maxwell began longwall production in April 2026. Its first stage targets approximately 3Mtpa of saleable coal.
The mine plans to increase longwall width in steps. Panels one and two use a 145-metre width, followed by 250 metres for panels three and four. From panel five, the planned width rises to 300 metres.
That staged approach sits behind the longer-term 5Mtpa longwall target.
The presentation also shows monthly production improving during commissioning. Those early monthly results have been annualised to illustrate progress; they should not be mistaken for a full year’s production.
The useful question now is whether Maxwell can sustain higher output as the mining sequence advances. A stronger month helps establish progress, but consistent performance across successive panels will matter more to annual results.
The Production Chart Needs Its Footnotes
Management explicitly describes these as indicative figures based on mine schedules, not production forecasts.
There is also an ownership change within the chart. Historical periods include New Hope’s 25.97% share of Maxwell, while the forward periods include 100%. Bengalla remains at 80% throughout.
Some of the increase therefore comes from owning more of Maxwell. The remainder depends on operating growth.
That distinction helps investors judge the Australian coal mining outlook at company level. Acquiring production and increasing a mine’s output can both expand reported tonnes, but they involve different spending and execution risks.
Further Growth Would Need Additional Approvals
Maxwell’s resource base offers development options beyond the current ramp-up.
An additional longwall in the Arrowfield seam would require a modification to the existing development consent, increasing approved run-of-mine production from 8Mtpa to 16Mtpa.
Extraction from the Warkworth seam also requires further regulatory approval. Maxwell North is a longer-dated opportunity, with environmental and technical studies underway.
These options should be kept separate from the operating mine’s approved life.
Growth Spending and Dividends Share the Same Cash
The companies present pro forma cash of approximately A$0.8 billion and net gearing of about 3%.
The cash figure combines New Hope’s position at 31 July 2026 with Malabar’s at 30 June 2026 and includes short-term investments. It is not a forecast of cash available on completion.
Management says the combined balance sheet would support growth while maintaining shareholder returns. Future dividends will still depend on operating cash generation, spending requirements and board decisions.
Colitco’s report on New Hope’s investor priorities discusses the balance between development and capital returns.
Approvals Come Before the Combined Growth Plan
The proposed timetable puts the Malabar scheme meeting in January or February 2027, followed by possible implementation in February or March.
Shareholder and court approvals remain outstanding, alongside regulatory conditions, including Japan Fair Trade Commission approval. All dates are indicative.
Colitco’s assessment is that Maxwell’s operating progress deserves as much attention as the transaction timetable. Completing the merger would establish ownership. Delivering the production targets would determine how much the enlarged portfolio contributes.
Investors should watch the scheme booklet, independent expert’s report and Maxwell production updates together. Those documents will help test both the offer terms and the growth assumptions supporting them.
ALSO READ: Global Markets vs ASX: Australian Coal Stock Performance
FAQs
Q1. Has the New Hope–Malabar merger been completed?
Ans. No. Completion is targeted for February or March 2027, subject to the required approvals and conditions.
Q2. What would Malabar shareholders receive?
Ans. 0.500 New Hope shares per Malabar share, subject to dividend adjustments under the transaction documents.
Q3. What is Maxwell’s production goal?
Ans. About 5.5Mtpa of salable coal in the longer term, comprising longwall and bord-and-pillar production.
Q4. Are FY27 and FY28 production numbers formal forecasts?
Ans. No. They are presented as indicative numbers based on current mine schedules.
Disclaimer
This article is solely for informational purposes and does not constitute financial advice. The transaction is subject to change and production targets may change. Please refer to the scheme documents and company announcements before making any investment decisions.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.