
Fortescue Ltd (ASX: FMG) remains a major dividend name among Australian miners. Yet its income outlook could change sharply in 2027. The company delivered record annual iron ore shipments during FY26.
It shipped 201.3 million tonnes after producing 52.7 million tonnes during the fourth quarter. Fortescue received US$91 per tonne for its ore in FY26. It expects shipments between 197 and 207 million tonnes this financial year.
However, rising operating costs could pressure future earnings. Investors must therefore look beyond Fortescue’s current dividend yield. The central issue is whether strong production can offset higher costs.
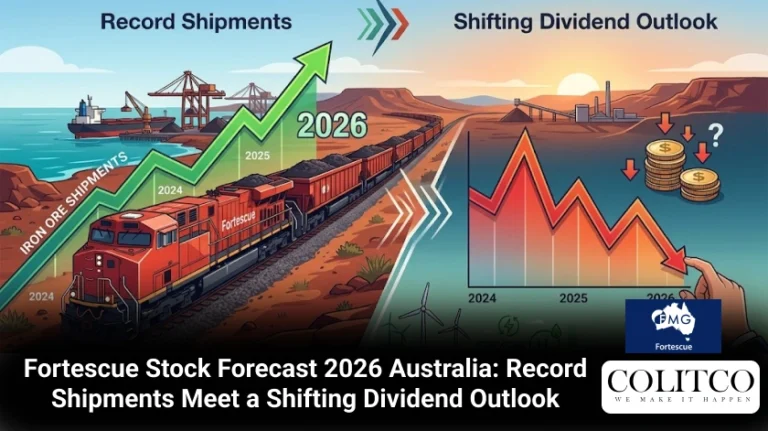
Fortescue’s record shipments support its dividend outlook despite rising costs. [Courtesy: Reuters]
Fortescue Shares Income Guide Australia: Current Dividend Picture
The company has historically been appealing with regard to high payouts. As per the source article, its trailing dividend yield is currently 6.78%, as recorded on the ASX. The yield is attractive for a passively held position.
However, trailing yields reflect previous dividend payments, not guaranteed future income. Fortescue’s dividend outlook depends heavily on earnings and commodity conditions. Iron ore prices remain an important driver of the company’s cash generation.
Costs also influence how much cash remains available for shareholders. Therefore, investors should treat the 6.78% yield as historical context. It should not be viewed as a fixed 2027 return. Fortescue traditionally pays dividends twice yearly.
What Could a $10,000 Investment in Fortescue Returns in 2027 Look Like?
The numbers provide a clearer picture of potential income. The company’s recent yield offers an attractive starting point for investors. However, Morgan Stanley expects a significant dividend reduction in FY27.
It predicts its dividend will be 60.6 cents per share. This is compared to FY26’s price of 112.9 cents a share. Morgan Stanley forecasts a dividend yield of 3.3% for FY27. Assuming that forecast, a $10k investment would yield approximately $330.
This is up from about $590 with a yield of 5.9% in the previous financial year. The difference highlights the potential income risk facing shareholders.
Morgan Stanley expects Fortescue’s dividend yield to fall to 3.3% in FY27. [Courtesy: Business Standard]
Why Fortescue Passive Income ASX 2027 Could Fall
Several factors could weaken Fortescue’s dividend capacity during FY27. Morgan Stanley expects the miner’s costs to rise significantly. Its forecast indicates FY27 C1 costs between US$20.50-21.75/wmt. The midpoint sits about 7.8% above the Visible Alpha consensus.
It also represents about 13% growth compared with FY26. Foreign exchange effects account for part of that increase. Other pressures include diesel costs, wages and inflation.
Longer haul distances could also increase absolute diesel consumption. These pressures may reduce earnings despite relatively stable shipment expectations. Investors should therefore monitor the following factors:
- Higher mining and transport costs.
- Iron ore pricing and realised prices.
- Foreign exchange movements.
- Dividend payout decisions.
These variables will shape potential income during 2027.
Earnings Pressure Could Change Fortescue’s Income Outlook
Morgan Stanley expects Fortescue’s earnings per share to decline 45% year on year. That forecast creates a major challenge for dividend-focused investors.
Lower earnings can reduce the amount available for shareholder distributions. Morgan Stanley expects Fortescue’s dividend yield to be 3.9% in FY28. The research also suggests the company could borrow to support dividends.
Fortescue still has a relatively healthy balance sheet, according to the analysis. Gross debt/EBITDA stands at 0.7x against a 2.0x company target limit. Gross gearing sits at 22% against a 40% limit.
Fortescue’s balance sheet remains stronger despite forecasts for weaker dividend earnings. [Courtesy: Kalkine]
What Investors Should Watch Before Buying FMG
Investors considering Fortescue shares should assess income and capital risks together. A high dividend can attract investors when commodity prices remain supportive. Yet mining dividends can change quickly when earnings weaken. Key considerations include:
- Sustainability of dividend: future payments are tied to earnings and cash generation.
- Iron ore exposure: Commodity prices have the capacity to have a significant impact on Fortescue’s profitability.
- Cost inflation: Diesel cost, wage and operating expenses may put pressure on margins.
- Share valuation: Morgan Stanley sees a ceiling on the share valuation at the present levels.
- Capital management: Borrowing to fund dividends may impact future financial flexibility.
Fortescue’s record production remains encouraging for investors. However, production alone cannot guarantee stronger shareholder income. The dividend outlook requires careful monitoring through FY27.
Fortescue Share Price Target Adds Another Risk
Dividend income is only one part of the potential investment return. Share price movements can also significantly affect a $10,000 investment. Morgan Stanley has set a $15.55 price target for Fortescue. That compares with $18.03 at the time of writing.
The valuation therefore creates another concern for investors. A falling share price could offset dividend income. Conversely, stronger iron ore prices could improve earnings expectations.
Fortescue’s expected shipment range also remains substantial at 197 to 207 million tonnes. The company’s ability to control costs will remain crucial. Investors should therefore assess total shareholder returns rather than dividend income alone.
Fortescue Passive Income ASX 2027: Final Investor Takeaway
The $10,000 investment in Fortescue returns 2027 outlook looks less generous than recent history. A 5.9% yield would have produced around $590 for a $10,000 investment. Morgan Stanley’s 3.3% FY27 forecast points towards approximately $330 instead.
That represents a sizeable potential reduction in annual passive income. Still, Fortescue remains a major iron ore producer with strong shipment volumes. Its record 201.3 million-tonne FY26 result demonstrates substantial operating scale.
The key challenge is maintaining profitability as costs rise. Income investors should watch dividends, costs, iron ore prices and earnings guidance. The final FY27 outcome could differ materially from current analyst forecasts.
Also Read: Santos Fuels the Western Hemisphere Comeback in Global Energy Markets
FAQs
- How much could $10,000 invested in Fortescue pay in 2027?
Ans: Morgan Stanley’s 3.3% FY27 yield implies approximately $330 in dividend income. Actual payments could differ from this forecast. - What was Fortescue’s recent dividend yield?
Ans: The trailing dividend yield cited in the article was 6.78%. However, historical yields do not guarantee future dividend payments.
- What is Morgan Stanley’s Fortescue price target?
Ans: Morgan Stanley has a $15.55 price target for Fortescue shares. That compares with $18.03 at the time of writing.
Disclaimer
This article is general information and does not constitute personal financial advice. The $10,000 income calculations use stated dividend-yield forecasts, not guaranteed payments. Fortescue’s dividends can change with earnings, iron ore prices, costs and board decisions. Share prices can also fall, reducing capital value. Investors should consider their circumstances and seek qualified financial advice before investing in FMG.
Source Links
- https://www.fool.com.au/2026/08/13/if-i-invest-10000-in-fortescue-shares-how-much-passive-income-will-i-receive-in-2027-2/
- https://www.fool.com.au/2026/07/27/by-july-2027-fortescue-shares-could-turn-10000-into/
Elizabeth Jones is a finance and mining content specialist with over 10 years of experience creating clear, SEO-driven content across fintech, investing, banking, insurance, cryptocurrency, and resource markets. She transforms complex financial data and industry trends into engaging, reader-focused articles that improve understanding and audience engagement.