
Something odd played out on the ASX floor this morning. QBE Insurance Group (ASX: QBE) walked out with numbers most insurance CFOs would frame and hang on a wall. Return on equity of 17.7%. A combined operating ratio holding at 92.8%. An interim dividend bumped 6% to 33 cents a share. And the stock closed at A$22.39, down 4.6% on the day.
That gap between the print and the price is the story.
Numbers that beat, a market that didn’t buy it
The scoreboard for the six months to 30 June 2026:
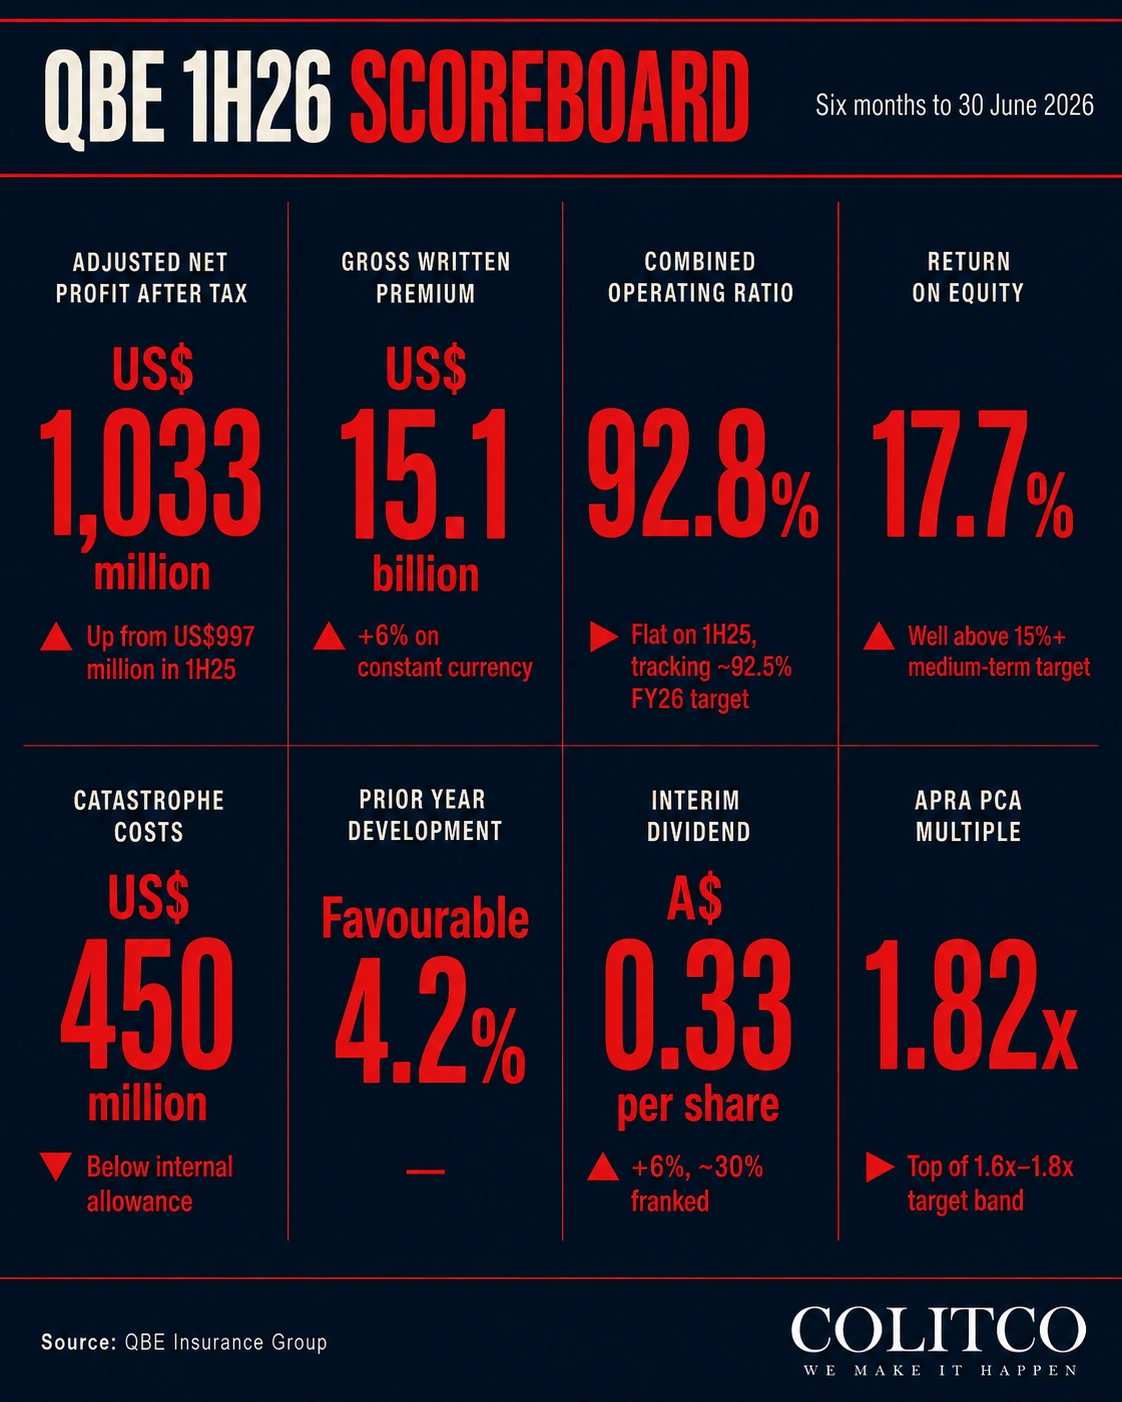
Overview of QBE 2026 Half Year Results [QBE]
By any conventional read, this is a clean print. QBE’s own guidance said mid-single-digit GWP growth and a combined operating ratio around 92.5% for the full year. Both boxes ticked.
So why the sell-off?
Middle East claims and one ugly contract hit sentiment
Buried in the presentation deck were two lines that gave the market pause.
First, an onerous contract provision inside the accident and health book. QBE flagged it as a full-year underwriting loss, meaning the current-period profit absorbed the hit for what’s still on the books through year-end. Not a rolling drag. Not quite a one-off either.
Second, roughly US$125 million tied to the Middle East conflict. About US$75 million landed in catastrophe costs, another ~US$50 million elsewhere. Material, though the overall cat number still came in comfortably below allowance.
Add ex-cat claims the company flagged as “timing-related matters” expected to improve in the second half of 2026, and the market did what it usually does with the word “timing”. Treated the promise as a maybe.
Capital moves are the quiet win here
The more interesting news for anyone watching the balance sheet sits behind the profit line.
QBE finished a A$450 million share buyback in April. It has now flagged the redemption of about A$500 million in Tier 2 notes on 25 August, which pulls the debt-to-total-capital ratio down to a pro-forma 22.4%.
Then there is the reinsurance engineering. A casualty sidecar for QBE Re plus fresh catastrophe bonds are together expected to free up around six percentage points of PCA benefit. In plain terms, that is capital available for more buybacks or writing more business into a market that is starting to firm again. Group CFO Chris Killourhy has been running this playbook for a while. The 1H26 print shows it is still on track.
Post-dividend, the pro-forma PCA multiple sits at 1.78x. Comfortably inside the target range, with headroom.
Australia Pacific goes quiet as competition returns
The domestic story is more nuanced. Australia Pacific GWP came in broadly stable on the prior corresponding period, with average premium rate increases holding in the low-single digits and volumes softening in a number of commercial portfolios where competition has picked up.
That is a shift from the double-digit rate story of the past few years. Brokers renewing books through the winter will notice. The pricing power that defined QBE’s local performance since 2020 is fading. Not gone, but fading.
Sue Houghton, the division’s CEO, announced her retirement. QBE says the search for her successor is well progressed. Whoever lands the seat inherits a book that is harder to grow in a market that is finally softening.
Board reshuffle lands mid-cycle
Yasmin Allen AM became QBE’s group chair, succeeding Michael Wilkins AO, while Christopher Harris joined the board on July 6 2026. Andrew Horton remains group CEO and used the results release to mark QBE’s 140th year, the company having been founded back in 1886.
Board turnover mid-cycle is worth flagging because insurers live and die on governance around reserving, capital and reinsurance. Continuity at the executive layer paired with a fresh chair suggests strategic direction will not shift, though capital allocation might get a second look.
What the sell-off actually tells us
A 4.6% single-day slide on a beat is not panic. It is expectation reset.
QBE had been trading near A$24.39 and was up 23% year to date going into the print. Analyst fair value was sitting around A$23.22. The stock is closer now to where consensus stands at A$22.39, and it seems like a better bet if the timing issue during H2 really comes through.
Takeaway for all who have been observing: good execution is not enough when expectations are already embedded and growth figures need to keep outperforming. The story from here depends on whether accident and health cleans up, whether Middle East exposure stabilises, and whether the Australia Pacific book can find growth without handing back rate.
FAQs
Q: What did QBE report for 1H26?
A: Adjusted net profit of US$1.03 billion, up 4%. Return on equity of 17.7%. Gross written premium of US$15.1 billion.
Q: Did QBE lift its dividend?
A: Yes. The interim dividend rose 6% to A$0.33 per share, franked at about 30%.
Q: Why did QBE shares fall despite the profit lift?
A: An accident and health provision, roughly US$125 million in Middle East-related impacts, and timing-related claims flagged for the second half unsettled the market.
Q: Who is QBE’s group CEO?
A: Andrew Horton remains group CEO. Yasmin Allen AM took over as group chair during the half.
Disclaimer:
This article is intended for informational purposes only and does not constitute financial product advice, investment advice, or a recommendation to buy or sell any securities. Readers should conduct their own independent research and seek professional financial advice before making any investment decisions. Past performance is not a reliable indicator of future results.
Source:
https://cdn-api.markitdigital.com/apiman-gateway/ASX/asx-research/1.0/file/2924-03120984-2A1689421
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.