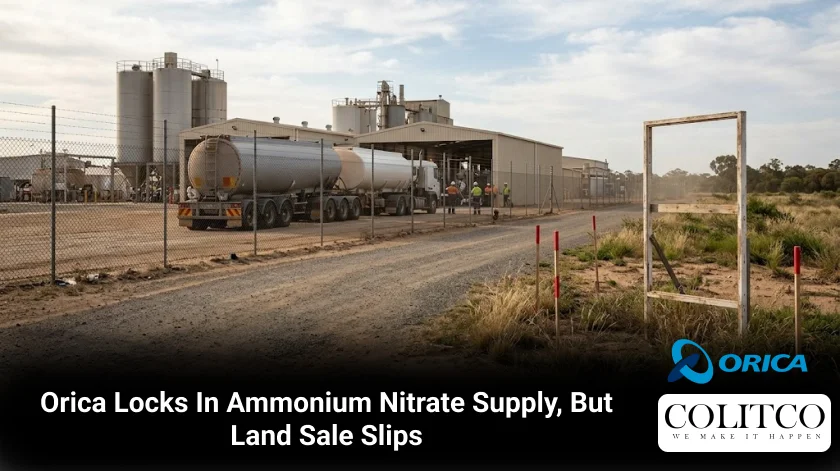
Orica (ASX: ORI) told the market on Monday, in its ASX announcement, that its North American customers are covered for FY2027. That year starts on Thursday.
The Deer Park land sale went the other way. Contracts were meant to be swapped in FY2026, which ends on Wednesday, and they will not be.
Two updates in one release, and they do not weigh the same. The supply news carries the story, and the history behind it shows why.
Ammonium nitrate supply now comes from a patchwork, not one plant
The trouble began on 5 November 2025. An incident at CF Industries’ Yazoo City plant in Mississippi halted its industrial ammonium nitrate output, and five days later CF claimed force majeure. That is a clause that lets a supplier step back from deliveries after an event outside its control.
Orica said the plant would not restart before the fourth quarter of calendar 2026 at the earliest.
That plant was the anchor. The supply deal tied to it covered up to 800,000 short tons a year, with an option running to 2031. In March, Orica agreed to pay US$169.5 million and the old purchase agreements were terminated. The full story sits in Orica’s settlement release.
Monday’s release lists where the tonnes come from now: US ammonium nitrate producers, extra output from the Carseland plant in Alberta, and Orica’s wider global network.
What it leaves out says plenty. No US supplier is named. No tonnage is given, and no price.
Swapping one giant supplier for several smaller ones spreads the risk. It also costs some bargaining power, because a buyer stitching together lots from many sellers tends to pay closer to the market rate.
Orica admits sourcing costs have risen.
How Orica’s North American ammonium nitrate sourcing has changed since the CF contract ended
| Item | Before Nov 2025 | FY2027 plan |
|---|---|---|
| Main outside supplier | CF Industries, Yazoo City, Mississippi | US producers (not named) |
| Volume disclosed | Up to 800,000 short tons a year | None disclosed |
| Orica-owned supply | Carseland, Alberta | Higher Carseland volumes |
| Global network | Not the primary source | Part of the core supply plan |
Higher costs land, but Orica says margins hold
Orica says the extra cost will not dent FY2027 margins in any material way. It points to lower logistics costs, cost-out work and customer arrangements.
That word, material, carries a lot of weight.
The first half showed what the bill looks like. Orica posted underlying earnings before interest and tax (EBIT) of A$600,000 after A$283.7 million of one-off items tied to the CF explosion.
Those costs were fenced off as one-offs. From October, the same costs become part of ordinary trading, and the fence comes down.
Nelson Brothers helps. Orica bought out its 50:50 partner in the US explosives business for US$25 million plus US$48 million in debt retirement, and expects an extra A$35 million a year in EBIT once it is fully bedded in. Monday’s release says the integration is finished.
The market looks relaxed. Shares traded at A$23.34, up about 2 per cent, in early trade on Monday. On the day the CF settlement hit the market in March, they dipped to A$19.23, so the stock is about 21 per cent higher since.
Deer Park land sale slips past the financial year-end
Explosives have been made at Deer Park, in Melbourne’s west, since about 1874.
Stage 1 covered 66 hectares. UniSuper paid A$260 million, and the deal settled in February 2024 for an after-tax profit of about A$173 million.
Stage 2 is the neighbouring parcel of roughly 68 hectares. Orica has long said it hinges on remediation, approvals and supportive market conditions.
Monday’s release blames market conditions and stops there. No price talk, no new date, no word on buyers.
Chief executive Sanjeev Gandhi put it this way: “We will remain disciplined in our approach to land divestments.”
Read that as a seller who will not take a low bid just to beat a year-end deadline.
Money is the angle worth a pause. The CF settlement works out to roughly A$242.5 million, paid from existing cash and undrawn debt. Stage 1 brought in A$260 million.
Orica has not linked the two. Still, a Stage 2 sale would have been a natural way to refill the tank.
Orica can afford to wait. Its first-half underlying result was the highest in more than 20 years, and Colitco’s note on the Orica first-half update covers the early signs.
Stage 1’s gain was booked as a one-off, and a Stage 2 gain would probably sit outside underlying earnings too. The delay shifts the timing of cash, not the earnings engine.
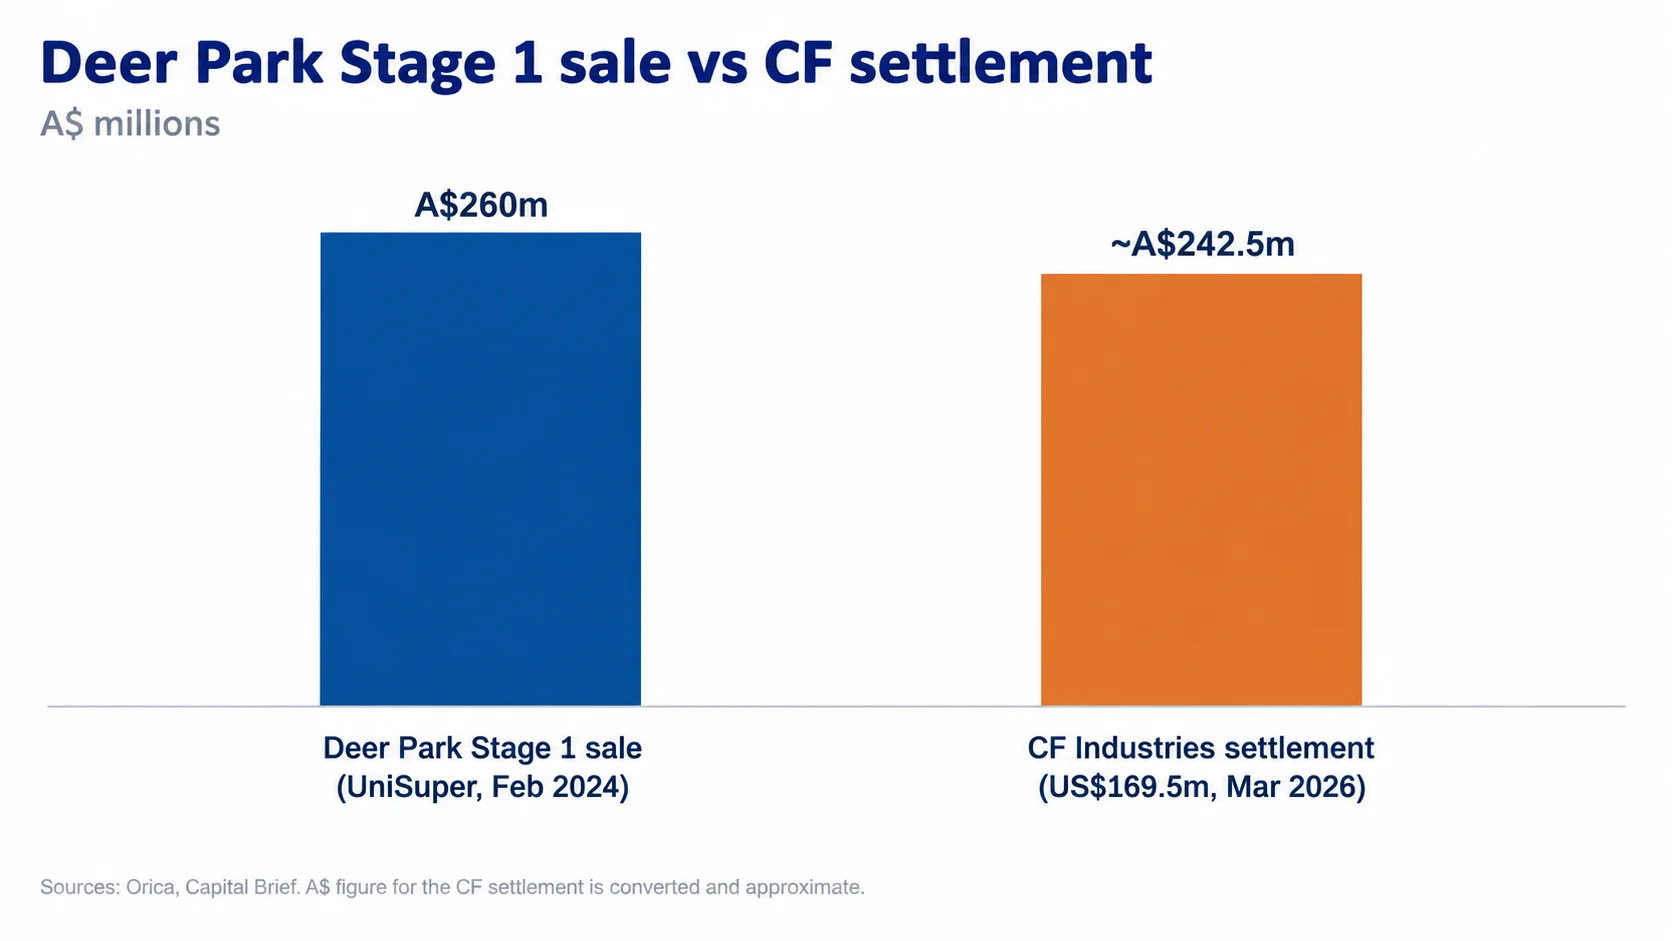
Deer Park Stage 1 proceeds sit close to the cost of the CF settlement. Orica has not linked the two.
November results will show the real cost of the supply fix
Orica reports full-year results in November, along with its FY2027 outlook. A few numbers will settle the argument:
- The dollar cost of FY2027 supply, not just the word “material”
- How much North American ammonium nitrate now comes from US producers versus Carseland
- Any new timing or price for Deer Park Stage 2
- Whether Yazoo City restarts on schedule and eases the US market
Ammonium nitrate is only one input. Gas is the other, and Orica’s non-binding gas deal with Santos for up to 15 petajoules a year shows the company has been lining that side up too.
Capital returns are the other pressure point, and our earlier note on the Orica on-market buy-back gives the background. Readers new to sector analysis can start with the guide on how to analyse ASX mining stocks or browse the mining news section.
Supply is fixed for now. The price of that fix is the number to wait for.
Also Read: IAG Greensill Settlement Ends $2.8bn Credit Suisse Claim
FAQs
Q: What did Orica announce on 28 September 2026?
A: It secured FY2027 ammonium nitrate supply for North America and pushed back the Deer Park sale.
Q: Where will Orica’s North American supply come from?
A: US producers, more output from Carseland in Canada, and its global network.
Q: Why was the Deer Park land sale delayed?
A: Orica points to changes in market conditions.
Q: Will higher sourcing costs hurt FY2027 margins?
A: Orica does not expect a material impact.
Q: How much did Deer Park Stage 1 sell for?
A: A$260 million, to UniSuper, in February 2024.
Q: When does Orica report next?
A: Full-year results are due in November.
Disclaimer: This article is general information only and is not financial product advice. It does not consider anyone’s objectives, financial situation or needs. Speak to a licensed financial adviser before making any investment decision. Colitco LLP may have commercial arrangements with companies mentioned or hold shares in them.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.