The Codan Eventide acquisition was announced on Monday 9 November, and the price carries a neat coincidence. Codan’s FY26 EBIT, its operating profit, was A$244.1m. The deal costs A$244m.
Just a coincidence. Still, it is a handy yardstick. A full year of earnings from drone radios, gold detectors and 911 software is about to buy one American company that most investors have never heard of.
What the Codan Eventide acquisition actually buys
Eventide dates back to 1971. Its recorders sit inside 911 call centres and control rooms, capturing calls, radio traffic, video and screen activity.
Think of a black box for an emergency call centre. When a response goes wrong or lands in court, Eventide’s gear holds the replay.
Codan says more than 9,000 Eventide recorders are in use across 80 countries. Over 4,000 sit in US 911 centres. Every one of those centres must run a recording system, so this is a compliance purchase. Compliance spending tends to stick.
The key terms, per Codan’s ASX announcement:
- Price: about A$244m, cash-free and debt-free
- Eventide CY26 revenue: about A$49m
- Eventide CY26 EBITDA: about A$17m
- Multiple: about 14x EBITDA, or about 10x with synergies
- Codan’s forecast: mid-single-digit EPS accretion in the first full year, synergies included
- Completion: early 2027
A$17m on A$49m of sales is a margin of roughly 35%. Buyers pay up for that.
One catch with the headline. A few market summaries tagged the price as US dollars. The footnotes in Codan’s release say every figure is Australian.
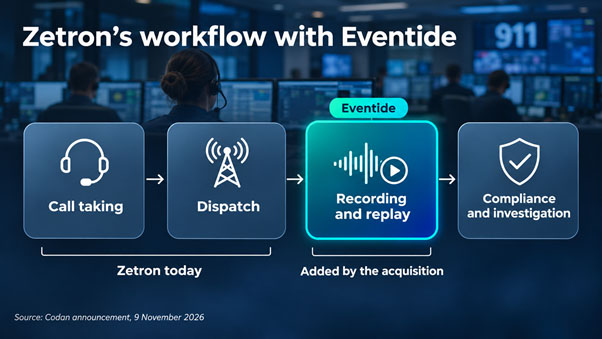 Eventide extends Zetron’s product chain from the emergency call through to evidence and review.
Codan buys Eventide to finish Zetron’s chain
Zetron already sells call taking and dispatch. Eventide adds the last step, recording and replay.
CEO Alf Ianniello says Zetron has resold Eventide for more than 10 years. Codan is buying a known partner, not a stranger.
The price history is striking. Codan paid US$45m, about A$59m, for Zetron in 2021. Eventide costs more than four times that. Its A$17m of EBITDA is also double the A$8m Codan forecast for Zetron in FY22.
Zetron’s recent run has been softer. Codan blamed slow buying by US state and local agencies in FY26, though Zetron’s order book still rose 25% by 30 June. Eventide arrives with earnings already in hand.
The risk is the part no spreadsheet prices. Eventide’s recorders also run alongside other 911 platform providers, and those are Zetron’s competitors. Codan’s release says Eventide’s US distribution network and interoperability stay central to its growth. It says little about keeping those rivals comfortable buying from a competitor’s subsidiary.
If a few start steering customers to another recorder brand, that A$49m begins to leak.
The Codan Zetron Eventide deal doubles as a drone hedge
Defence made up 58% of Communications revenue in FY26, up from 38% a year earlier. Unmanned systems alone brought in roughly A$215m.
Codan’s release talks about more “non-conflict revenue streams”. Translation: war-driven order books do not last forever, and Codan would rather add earnings that do not depend on one. A 911 recorder fits. Nobody cancels one because a ceasefire arrives.
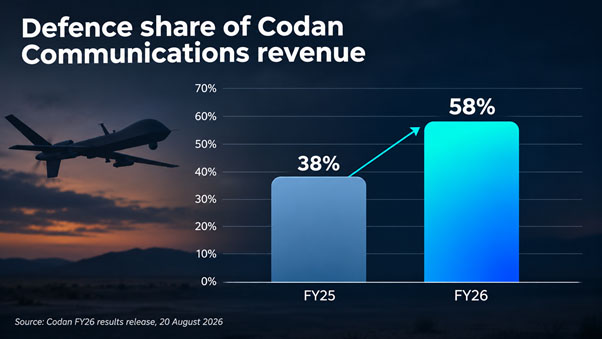 Defence customers now supply well over half of Codan’s Communications revenue.
The timing is kind. Shares dipped early on Monday, then closed about 2.7% higher at A$55.98, per Market Index. They traded near A$43.50 when the FY26 result landed on 20 August.
Funding looks comfortable. Codan ended June with net cash of A$35.7m. A new A$80m credit facility lifts its committed debt lines to A$330m. The roughly A$11m of shares goes to Eventide’s managing director in yearly instalments over three years.
By this desk’s rough sums, borrowing the full cash bill of about A$233m would leave net debt under 1x FY26 EBITDA of A$288.9m. Codan’s A$244m acquisition is also only about 2.4% of its market value, which sits near A$10bn. No ASX Codan acquisition in the past five years comes close to this size, yet the balance sheet barely flinches.
Small print behind a A$244m cheque
Eventide became its own legal entity only in 2023, split from sister companies Eventide Inc. and Eventide Audio. It still leans on one of them. Under a transitional services agreement, Eventide Inc. will keep running Eventide’s admin, IT, HR, procurement and inventory for six months, with an option for six more.
So the business being bought still borrows its back office.
Codan puts integration costs at about A$4m in FY27. Matthew Schwartz, Eventide’s managing director and CTO, is staying with the senior team. His deferred shares tie his payout to Codan’s share price.
Eventide launched Critical Insights AI in 2025. It is a cloud add-on for transcription, translation and call quality checks. Codan expects recurring revenue from it. The A$244m pays for the recorder business, so any AI income is a bonus.
Three checkpoints matter from here: completion in early 2027, the first Zetron sales of Eventide outside the US, and any rival platform dropping Eventide.
The price is fair for what Eventide earns. The real test is rival loyalty, not the first year of accretion.
Also Read: How Macquarie Group’s Business Diversification Is Reshaping Its Earnings Structure in 2027
FAQs
Q: How much is Codan paying for Eventide?
A: About A$244m, cash-free and debt-free.
Q: Who is selling Eventide?
A: Its founding partners and managing director.
Q: How is the deal funded?
A: Cash, a partial debt drawdown and up to about A$11m of deferred Codan shares.
Q: When will it close?
A: Early 2027, subject to regulatory conditions.
Q: Will it lift earnings?
A: Codan expects mid-single-digit EPS accretion in the first full year, including synergies.
Disclaimer: This article is general information and analysis only. It is not financial advice and does not consider personal circumstances. Share prices and figures change. Readers should do their own research or speak to a licensed adviser before making investment decisions.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.