Five businesses can grow and produce quite different outcomes for their owners. A Coles shareholder might get the supermarket earnings they expected and still be disappointed with the share price.
At Goodman, even the month a tenant starts paying rent can alter a year’s result. Colitco examines what buyers of ASX growth stocks would need to see from each business before putting a value on FY2030 earnings.
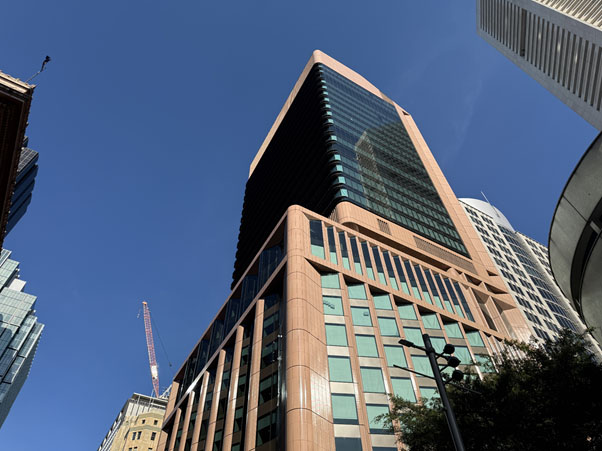
Figure 1: The Australian Securities Exchange head office at 39 Martin Place, Sydney, photographed on 29 September 2025. Credit: Klauskazamias, Wikimedia Commons (CC0).
CSL: Where Did the Extra Sales Dollars Go?
In FY2025, CSL Behring earned USD 50.60 in gross profit for every USD 100 of revenue. A year later, it earned USD 49.60 on the same basis. A dollar sounds modest.
Across a division with more than USD 11 billion in annual revenue, that one percentage point was enough to absorb most of the benefit of higher sales.
| CSL Behring | FY2025 | FY2026 |
| Revenue | USD 11.158 billion | USD 11.387 billion |
| Gross profit | USD 5.641 billion | USD 5.648 billion |
| Gross margin | 50.6% | 49.6% |
For CSL (ASX: CSL), recovering even part of that lost margin could make a difference. At FY2026 revenue, half a percentage point would be worth roughly USD 57 million in annual gross profit. That is an illustration, before selling expenses, interest and tax.
The next set of Behring accounts will allow a straightforward check. If revenue rises again, how much of the increase makes it to the gross profit line?
Coles: What Would Put AUD 26.22 a Share Within Reach?
The Coles (ASX: COL) scenario assumes earnings per share grow by about 7% a year through FY2030. At that point, a buyer would have to pay 23 times annual earnings to arrive at AUD 26.22 a share. Against the November price used in the comparison, that would represent a gain of roughly 18% over four years, before dividends. It is neither an annual return nor company guidance.
Consider the assumptions separately. On the supermarket floor, keeping prices low can bring customers back for their next weekly shop. It leaves Coles with a problem, though: if the customer buys much the same basket for less, where does the extra profit come from?
Lower handling costs at automated distribution centres could help. The evidence would be sales holding up without a further squeeze on the supermarket margin.
The second assumption is outside Coles’ control. A price of AUD 26.22 at 23 times earnings implies annual earnings of AUD 1.14 a share. A buyer willing to pay only 20 times would offer AUD 22.80 for the same business result. That AUD 3.42 difference has nothing to do with how many groceries Coles sold.
Commonwealth Bank: What Is a New Mortgage Worth to Shareholders?
A borrower refinancing a home loan wants the sharpest rate available. A Commonwealth Bank shareholder has a different interest in that negotiation. A large mortgage won on a thin margin may add less to profit than its size suggests.
For Commonwealth Bank (ASX: CBA), loan growth therefore belongs beside two other figures: net interest margin and credit losses. Together they help explain whether writing more business is improving earnings or simply making the loan book bigger.
Then there is the price of buying into the bank. Take a hypothetical share worth AUD 100. Suppose earnings per share rise 20% by 2030 while the multiple buyers will pay falls 20%.
The share would be worth AUD 96. Dividends would count towards the holder’s return, but even someone who correctly forecast the bank’s earnings could have overestimated its final share price.
Goodman: When Will Tenants Start Paying Rent?
In September 2026, Goodman Group (ASX: GMG) raised USD 455 million of equity for its Hong Kong Data Centre Partnership. The partnership had capital to put to work. That did not mean Goodman securityholders had earned USD 455 million or that a tenant had paid its first month’s rent.
A six-month lease start date discrepancy explains why time matters. A January payer pays a year’s rent. Starting in July means just six months in a year, even if the client takes the same space at the same fee. Construction progress and electricity availability affect that date.
The best 2030 estimate would include when rent begins, how much cash Goodman has invested, and what portion of the land it owns. A headline development value cannot address such issues.
WiseTech: What Happens Once e2open Is in Both Years’ Figures?
WiseTech Global (ASX: WTC) first-half FY2026 sales rose 76% to USD 672 million. Adjusting for acquisitions and currency moves, organic growth was 7%. One rate describes how much bigger the group became; the other gives a better sense of the pace inside the existing business.
The e2open acquisition gave WiseTech existing customers. That was a big leap in the first comparison. Once e2open income emerges on both sides of the yearly comparison, owning the company no longer lifts.
By then, shareholders should know whether customers renew, purchase more software, and what operational cash remains after integrating the firms. Another year of increased sales would be more significant if cash generation improved.
What Could Change the 2030 Outlook First?
For readers keeping a list of ASX stocks to watch, there is little need to wait four years to find out whether an assumption is wrong. A Coles result can show whether lower shelf prices cost more than distribution savings delivered.
A Goodman update can shift a lease commencement into the following financial year. Either disclosure could justify revising a forecast well before 2030.
Useful ASX stock analysis starts with a number that would change the investor’s mind. At CSL Behring, that number may be gross margin.
At CBA, it may be the price asked for the shares themselves. A good set of bank results can settle the question of how the business performed. Whether a buyer paid too much for it remains a separate calculation.
ALSO READ: ASX Mining Valuations: What Could Drive the Next Repricing?
FAQs
Is AUD 26.22 an Official Coles Price Target?
No. It is an illustrative FY2030 valuation based on assumed earnings growth and a final price of 23 times earnings. It is not company guidance.
What Would an 18% Gain Over Four Years Mean Annually?
Roughly 4.2% a year on a compounded basis, before dividends. It does not mean shareholders would earn 18% each year.
Why Does Goodman’s Partnership Structure Matter?
A partnership can fund and own a development without all its rental income belonging to Goodman. The group’s ownership interest affects how much of that income is attributable to it.
Which WiseTech Figure Is More Useful for Estimating Future Growth?
Start with revenue to determine combined company size. Use organic growth to estimate how fast the firm may develop without an acquisition.
Disclaimer: This is general information, not financial advice. The FY2030 values represent possibilities, not corporate estimates. Earnings, dividends, and share prices vary.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.