Thursday, 1 October brought a joint ASX announcement, a binding deed and one number that led every headline.
Lynas hands Meteoric holders 0.0207 of its own shares for each one they own. In return, it gets Caldeira, an ionic clay rare earths project in Brazil.
The A$968 million was set on a Lynas share price that no longer exists
That figure uses Lynas’s 60-day average price of A$15.29. The last close before the announcement was A$13.83, which puts the equity value at A$876 million, by the company’s own numbers.
Then trading opened. Lynas finished Thursday at A$12.64 after an 8.6% slide, which puts the offer at about A$801 million on the same basis. That works out to roughly 26.2 cents a Meteoric share.
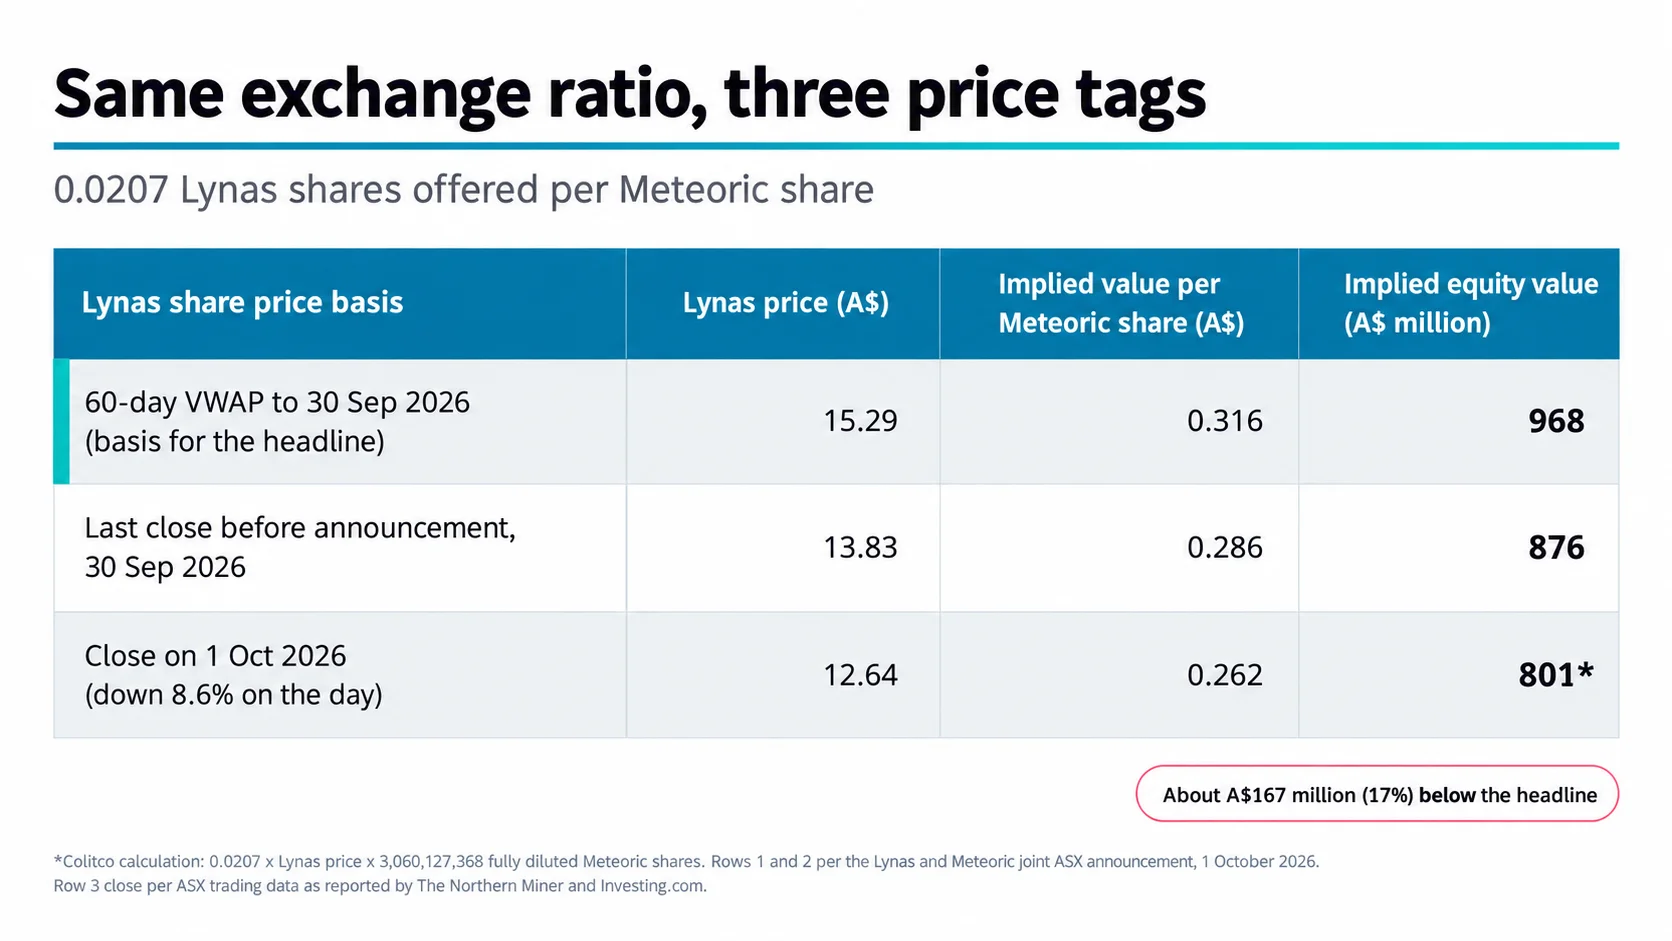
Table showing the Lynas Meteoric deal value
Meteoric closed up 47% at about 25 cents. That sits close to the implied value, so the market is betting the deal gets done.
The ratio is fixed. Until the scheme closes, Meteoric holders wear every move in Lynas stock, and a 68.4% premium to last close only holds if the currency holds too.
Caldeira adds 79% to the resource base for about 6% of the company
Meteoric holders end up with roughly 5.9% of the enlarged group. Caldeira would make up 44% of the combined rare earth resource and 21% of the reserve, according to the investor presentation.
Inside the ground sit 1,631 million tonnes at 2,317 parts per million. That holds 802,000 tonnes of NdPr oxides and 41,000 tonnes of dysprosium and terbium oxides. The heavy stuff is what Lynas wants, because it is scarce outside China.
Now the footnotes. The 79% jump adds two separate estimates together, and the filing says it is not a new combined resource.
Only 151 million tonnes of Caldeira sits in reserve, under a tenth of the resource. That reserve alone backs the 23-year mine life, and the study left out more than 80% of the tenure.
The 3,862 tonnes a year of NdPr is a production target, not a forecast. The filing says so more than once.
The Bull’s write-up put Caldeira’s spot-price NPV at A$1.21 billion, which would sit above all three price tags.
The Meteoric Resources takeover carries costs the headline leaves out
- Lynas will lend Meteoric up to A$110 million, but only A$35 million arrives at signing. The other A$75 million needs the deed to be alive after six months, with the end date extended. Interest runs at 10%, capitalised and unsecured, and Meteoric held about A$38 million in cash at 30 June.
- Law No. 15,506 is dated 16 September 2026. Two weeks later, a change of control at a critical minerals holder needs approval from a brand new council. Meteoric’s executive chair, Andrew Tunks, said Lynas had spoken to Brazil’s federal government and the development bank BNDES “to ensure no delay in the development of Caldeira.”
- The end date is six months after signing, so about 1 April. Implementation is targeted for early March. That leaves around four weeks of slack, with a three-month extension on offer.
- The landholder holding the exclusive mining right agreed to move its termination trigger from April 2031 to April 2033. If operations have not started by 2031, payments of US$600,000 a month begin, plus a second US$600,000 that cannot be credited against future payments. Run the full two years and that is US$28.8 million, with US$14.4million gone for good.
- Break fee. A$8.8 million each way is under 1% of the headline. A rival bidder would not be scared off by the penalty alone, though Lynas holds a matching right.
Then there is the build. Initial capex is US$498 million, about A$717 million at the exchange rate implied by the reported deal values. That is around 60% of Lynas’s A$1.2 billion in cash.
Paying in shares protected the cash. The construction bill will spend it.
We covered the earlier Caldeira study in March, before the definitive feasibility study landed in July.
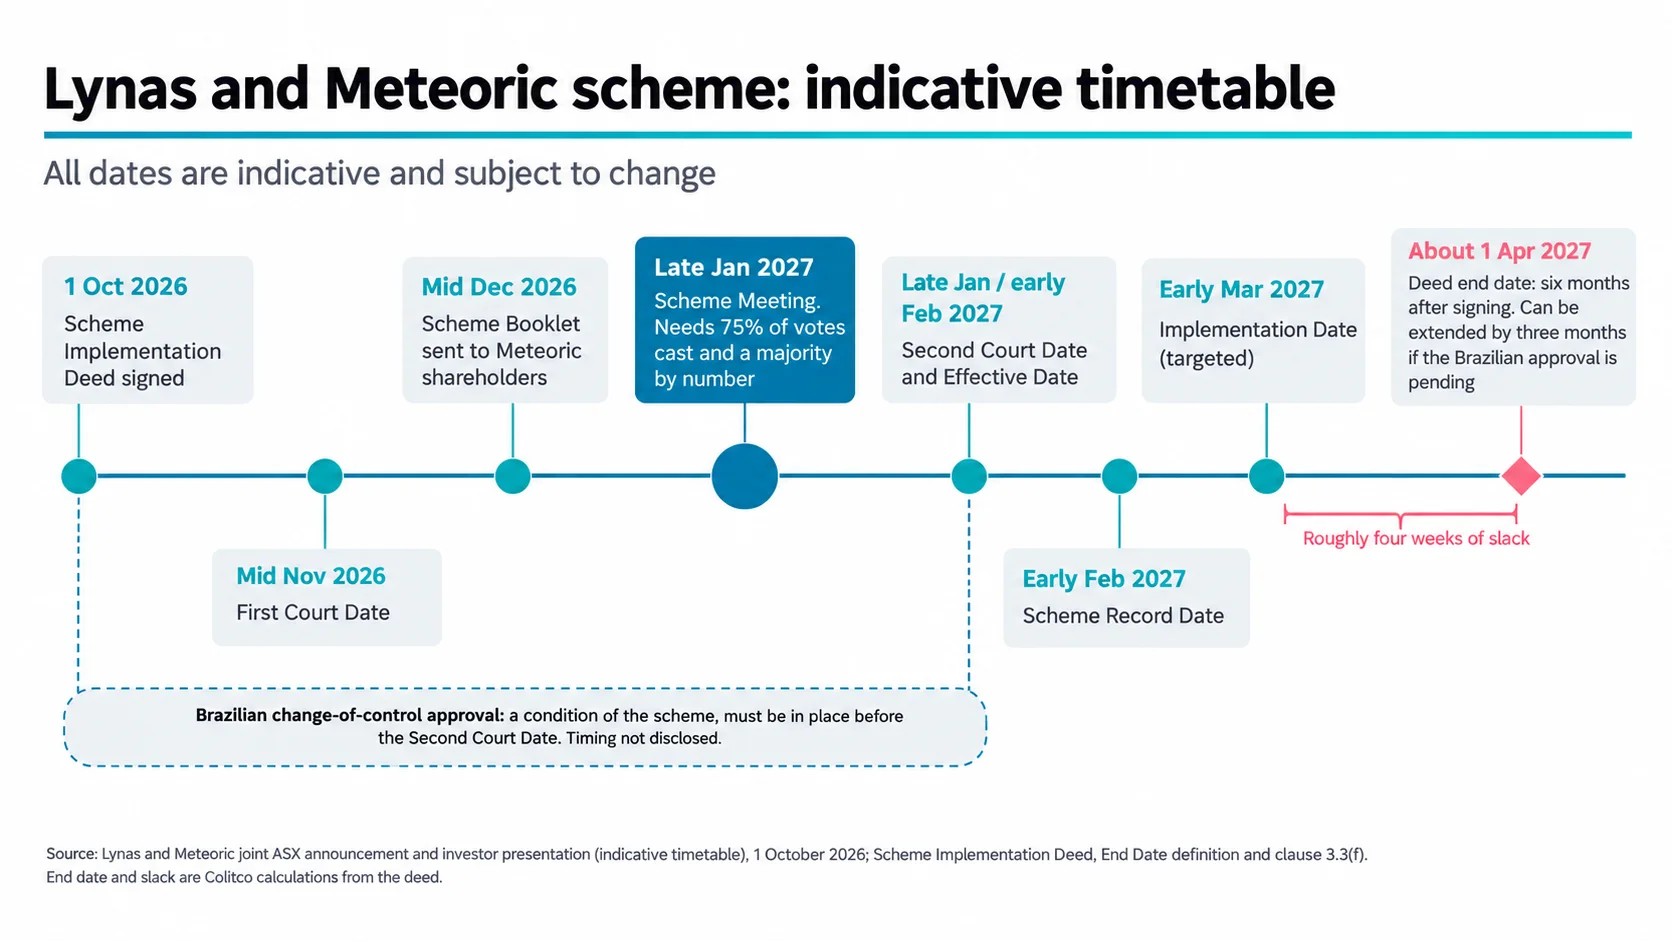
Timeline of the Lynas Meteoric scheme from signing in October 2026 to implementation in March 2027.
Ionic clay is new ground for Lynas, and the chief executive’s chair sits empty
Everything Lynas runs today starts with hard rock from Mt Weld. It then moves through the Kalgoorlie processing facility and the Kuantan plant, where a heavy rare earth separation plant is part of the growth plan. Ionic clay is a different beast.
Terra Capital analyst Dylan Kelly said the technical risk of processing ionic clay worried him, and asked, “what are Lynas shareholders paying for here?” Macquarie held its outperform rating but shaved its Lynas price target to A$19 from A$20.
Amanda Lacaze left in June, and Chair John Humphrey expects to name her replacement before the 25 November annual meeting. Whoever lands the job inherits a US$498 million Brazilian build they did not choose.
My read is that the strategy holds up. Heavy rare earths from a second country is what Western buyers keep asking for, and Lynas describes itself as the only commercial producer of separated light and heavy rare earth oxides outside China. That also fits the wider push for non-Chinese supply.
The price and the execution are the open questions. Three checkpoints will answer some of them: the Scheme Booklet with the independent expert’s report in December, the Scheme Meeting in January, and the installation licence Meteoric was targeting for this year.
Also Read: Amplitude Energy FID Comes With a Side Bet
FAQs
Q: How much is Lynas paying for Meteoric?
A: The headline is A$968 million at Lynas’s 60-day average, or A$876 million at last close.
Q: What do Meteoric shareholders receive?
A: They get 0.0207 new Lynas shares per Meteoric share, about 5.9% of the enlarged company.
Q: When will the deal complete?
A: Implementation is targeted for early March 2027, pending votes, court and Brazilian approval.
Q: Where is the Caldeira project?
A: It sits in Minas Gerais, Brazil, about 254km from São Paulo.
Q: Can a rival bid still appear?
A: Yes, but exclusivity terms apply, and Lynas holds a matching right.
Disclaimer: This article is general information only and is not financial advice. It does not consider your objectives, financial situation or needs. Mining and exploration stocks carry high risk. Speak to a licensed financial adviser before making any investment decision.
Elizabeth Jones is a finance and mining content specialist with over 10 years of experience creating clear, SEO-driven content across fintech, investing, banking, insurance, cryptocurrency, and resource markets. She transforms complex financial data and industry trends into engaging, reader-focused articles that improve understanding and audience engagement.