Fortescue Ltd (ASX: FMG) reported weaker sales for the September 2026 quarter, and China is at the centre of it. The preliminary update, lodged on 8 Oct 2026, links the shortfall to ongoing talks with China Mineral Resources Group (CMRG).
Fortescue China relations now drive the Company’s near-term story. Shipments, sales and cash all moved the wrong way during the quarter.
Fortescue Iron Ore Sales Trail Shipments as CMRG Talks Drag On
Fortescue iron ore sales came in at 42.9 million tonnes in the first quarter of FY27 (Q1 FY27). Shipments were higher at 46.8 million tonnes, the ASX release shows. Bloomberg reported that sales ran about 8 per cent below shipments.
The Company said the gap reflected “impacts from ongoing negotiations with China Mineral Resources Group”. It also pointed to maintenance, including scheduled port outload shutdowns.
Shipments were six per cent lower than Q1 FY26 and included 2.5 million tonnes from Iron Bridge. Stocks across the supply chain remained healthy at quarter end.
Pricing and Cash Flow Show the Strain Behind the Headline Volumes
| Metric | Q1 FY27 |
| Total iron ore shipments | 46.8 million tonnes |
| Iron Bridge shipments | 2.5 million tonnes |
| Iron ore sales | 42.9 million tonnes |
| Hematite realised price | US$80 per dry metric tonne |
| Share of average Platts 61% CFR Index | 82 per cent |
Net operating cash flow was hit by higher working capital, including increased product inventory. Fortescue held more ore than it sold, and that ties up cash.
Cash Falls and Net Debt Climbs After a Heavy Quarter
| Measure | 30 Sep 2026 | 30 Jun 2026 |
| Cash | US$3.2 billion | US$5.1 billion |
| Net debt | US$2.8 billion | US$0.9 billion |
The June cash figure comes from Reuters. Reuters reported that cash fell 37 per cent and net debt more than tripled.
The Company paid its FY26 final dividend of US$1.0 billion during the quarter. Capital expenditure was US$0.9 billion.
Fortescue China Tensions Centre on CMRG’s Push for Pricing Power
CMRG Seeks a Bigger Role in Contract Talks
CMRG wants to consolidate buying power and push for better pricing terms on Fortescue’s products. The reason is simple. CMRG was created to consolidate China’s iron ore buying and pricing power. Reuters reports it is seeking better terms for domestic steelmakers.
Earlier this year, Reuters reported, CMRG asked some mills not to take delivery of Fortescue’s flagship product. Bloomberg reported that CMRG also told steel mills and traders it planned to restrict some Fortescue products. China is the world’s largest iron ore importer by a wide margin.
BHP’s April Agreement Sets the Backdrop for Fortescue’s Talks
BHP Group (ASX: BHP) was locked in a standoff with CMRG for months before reaching an agreement in April. The sources reviewed report no comparable outcome for Fortescue.
Fortescue has said CMRG’s actions undermine the market. It is exploring alternative customers to reduce the dispute’s impact, according to Bloomberg.
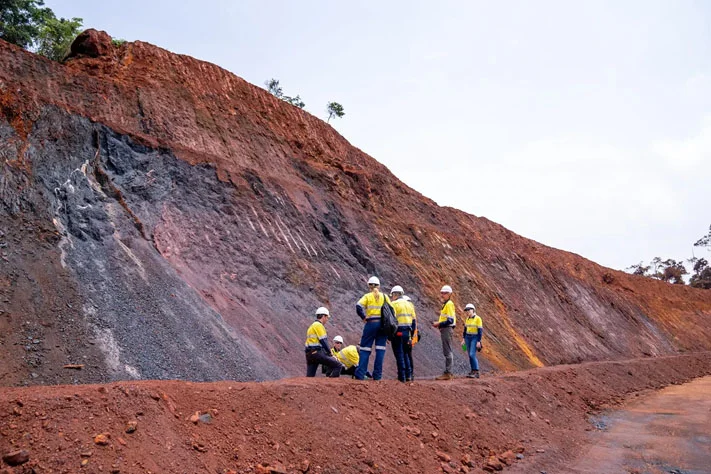
Figure 1: Geologists and mine staff inspect an exposed iron-rich rock face at an open-cut site [Courtesy: Fortescue]
A Fourth-Largest Iron Ore Miner Led by Andrew Forrest
Bloomberg describes Fortescue as the fourth-biggest iron ore miner. The Company is led by Executive Chairman Andrew Forrest.
Operations referenced in the sources include Christmas Creek and the Iron Bridge mine. Reuters noted that Fortescue is exploring ways to lift port outload capacity at Iron Bridge.
Industry Outlook
| FY27 guidance item | Status |
| Iron ore shipments | Unchanged, subject to CMRG negotiations |
| C1 unit cost | Unchanged, subject to CMRG negotiations |
| Capital expenditure | Unchanged, subject to CMRG negotiations |
The Fortescue iron ore outlook therefore rests on talks that have not concluded. The Company has not confirmed when they will end. Any change in terms could affect sales, pricing and working capital.
Bloomberg reports that China takes most cargoes from Australian and Brazilian miners. CMRG’s consolidated buying role is changing how those miners negotiate. BHP’s April agreement shows these disputes can end, though terms for Fortescue remain unconfirmed.
Share Price Performance
- Last price: A$15.79 as at 8 Oct 2026
- Market capitalisation: A$49.29 billion
- 52-week range: A$15.335 to A$23.380
- Early trading: down 1.8 per cent at A$15.77, according to Reuters
- Intraday low: down as much as 3.5 per cent, according to Bloomberg
- Peer comparison: BHP and Rio Tinto fell by less in the iron ore mining sector
Future Direction and Impact
Fortescue will release its September 2026 Quarterly Production Report on 22 Oct 2026. Investors will look for more detail on sales, inventory and the CMRG talks.
Impact on cash flow: inventory built during the quarter has not yet been converted into sales. Impact on supply: shipments remain tied to maintenance schedules and any port outload expansion at Iron Bridge.
Colitco will keep tracking the CMRG negotiations and report any confirmed outcome.
ALSO READ: Strata Minerals Completes BML Placement as Zelica Gold Project Enters Key Q4 Phase
FAQs
Q1. Why did Fortescue iron ore sales fall below shipments?
Ans. The Company linked the gap to ongoing negotiations with CMRG.
Q2. Has Fortescue changed its FY27 guidance?
Ans. No. Guidance is unchanged but remains subject to CMRG negotiations.
Q3. When is the full production report due?
Ans. Fortescue will release it on 22 Oct 2026.
Q4. Why does CMRG matter to Fortescue’s iron ore outlook?
Ans. CMRG consolidates China’s iron ore buying, and Fortescue’s FY27 guidance remains subject to the outcome of its negotiations.
Disclaimer
This article is meant only for informational purposes. If you are an investor who is watching Fortescue Ltd closely, all the data published in the content is sourced from ASX announcements and external sources. Kindly verify all the information related to the share price and market data. Any investment should be made at the investor’s own risk. Colitco does not hold any position in the above-mentioned company.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.