The Kalkaroo Copper Project has spent years on the list of potential Australian developments. Drilling is now testing the deposit for a new study, while Havilah considers returning part of the deal proceeds to shareholders. In this article, Colitco explains what Sandfire has committed, what remains conditional and why progress on a study is different from approval to build a mine.
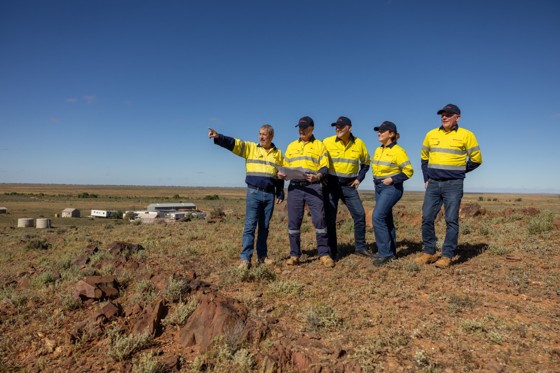
Figure 1: A site visit at Kalkaroo in South Australia, pictured in Sandfire’s June 2026 project update. Archive photograph. Credit: Sandfire Resources.
The First Payment Gives Havilah Value Before Production
Under the February agreements, Sandfire paid AUD 31.5 million in cash and issued 4,640,833 shares to Havilah. Together, these formed the agreed AUD 105 million Stage 1 consideration. The share component means the market value of what Havilah holds can change.
That is a different position from an explorer funding every round of work through another share issue. Havilah has received consideration while Sandfire funds the new study. It has not, however, received the second payment or begun collecting revenue from Kalkaroo production.
| Commitment | Amount | Purpose |
| Stage 1 | AUD 105 million | Upfront consideration; paid |
| Stage 2 | AUD 105 million | Further consideration to acquire 80% |
| New study | About USD 70 million | Drilling and pre-feasibility work |
| Regional alliance | At least AUD 30 million | Exploration over the initial two years |
These are separate commitments. The study budget is not a construction estimate, and regional exploration money should not be counted as another payment for the same project interest.
Sandfire’s Right to Acquire 80% Still Has to Be Exercised
Havilah’s 2026 annual report describes Sandfire as holding an exclusive right to acquire the interest, with no interest yet acquired at the reporting date. Stage 2 requires a further AUD 105 million consideration, payable in a combination of cash and shares under the agreement.
If that stage is completed, Havilah would retain 20%. Investors should therefore distinguish the commercial pathway from the ownership position already achieved. Describing Sandfire as the present 80% owner would skip a material step.
For Havilah, a smaller interest alongside an experienced operator may offer a more practical route to development than sole ownership. The trade-off is participation in a smaller share of any eventual project returns. Whether that proves attractive depends on the mine that can be designed, funded and operated.
More Drilling Tests Both Size and Confidence
The planned programme extends well beyond the agreement’s minimum drilling commitment. Sandfire has outlined approximately 130,000 metres of infill and extension drilling. Its site work followed approval of a Program for Environmental Protection and Rehabilitation, with further approvals still to follow.
Infill and extension holes answer different questions. Infill work tests the ground between existing holes, helping engineers judge how reliably mineralisation can be carried into a mine plan. Extension drilling looks beyond the established boundaries.
A longer drilling programme does not guarantee a larger profitable mine. Additional material may be deeper, lower grade or more expensive to reach. The useful result is a better-supported estimate of what can be mined and processed, rather than metres drilled alone.
That is the next test for the Havilah Resources copper strategy: whether the geological work improves the development case enough to justify the next commitment.
The Study Must Turn a Deposit Into an Operating Plan
Sandfire describes an existing reserve of about 100 million tonnes grading 0.47% copper and 0.44 grams per tonne gold. Kalkaroo is roughly 90 kilometres west-north-west of Broken Hill, on the South Australian side of the border.
Those figures establish scale, but they do not specify what a future operation will earn. The new study must connect the deposit with a mining sequence, processing design, infrastructure requirements and an estimate of the money needed before customer receipts begin.
Colitco’s analysis of ASX mining valuations explains why the timing and cost of future cash flows matter alongside the amount of metal in the ground. A larger resource can be encouraging while leaving important financing questions unanswered.
The roughly USD 70 million study programme is targeted for completion in the second half of FY2028. That is a study milestone, not a first-production date for the proposed Kalkaroo Copper Mine.
The Share Distribution Offers a Separate Investor Decision
The November proposal would distribute part of Havilah’s Sandfire holding to shareholders. The announced components are a fully franked dividend of 7.514 cents per Havilah share and a proposed capital reduction of 5.085 cents, with the latter requiring shareholder approval.
The distribution is intended to be made in Sandfire shares rather than cash. Its final allocation depends on the pricing mechanism and applicable terms. A stated value per Havilah share is therefore not a promise that a fixed cash amount will arrive in a bank account.
This gives shareholders two exposures to consider: the Havilah business they continue to own and any Sandfire shares they receive. Neither should be treated as a guaranteed gain merely because the assets are being distributed.
The Next Milestones Are More Useful Than a Share-Price Target
- Drilling results: do the new holes improve confidence in the deposit or identify material beyond its current limits?
- Study scope: what changes in plant size, recovery assumptions, infrastructure and development costs?
- Stage 2: does Sandfire exercise its acquisition right and satisfy the further consideration?
- Shareholder distribution: what terms are approved, and what final allocation is announced?
Havilah now has a development partner doing substantial work on the asset. That is meaningful progress. The investment case will become clearer as the study replaces broad expectations with engineering and cost estimates. Until then, the next milestone is a better-defined project, not an operating mine.
ALSO READ: Copper Miners Rally After Congo Disruption Shakes Global Supply
FAQs
Does Sandfire Already Own 80% of Kalkaroo?
The disclosed arrangement gives it an exclusive right to acquire that stake. The first payment alone does not complete the acquisition.
When Is the New Study Expected?
Completion is targeted for H2 FY2028. A study completion date does not establish when construction or production will begin.
Is the USD 70 Million Figure the Cost of Building the Mine?
No. It refers to the planned pre-feasibility study programme, including drilling, rather than a mine construction budget.
Will Havilah’s Proposed Distribution Be Paid in Cash?
The proposal is an in-specie distribution of Sandfire shares. Shareholders should check the final terms and relevant tax treatment.
Disclaimer: This article provides general information, not personal financial or tax advice. Study schedules, acquisition rights and proposed distributions remain subject to their disclosed terms. Project development and investment returns are not guaranteed.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.