One of the larger expenses in the ANZ New Zealand financial results 2026 came from a court case. Another came from the less conspicuous business of paying for software licences and outsourced services. Here’s what changed in the financial results.
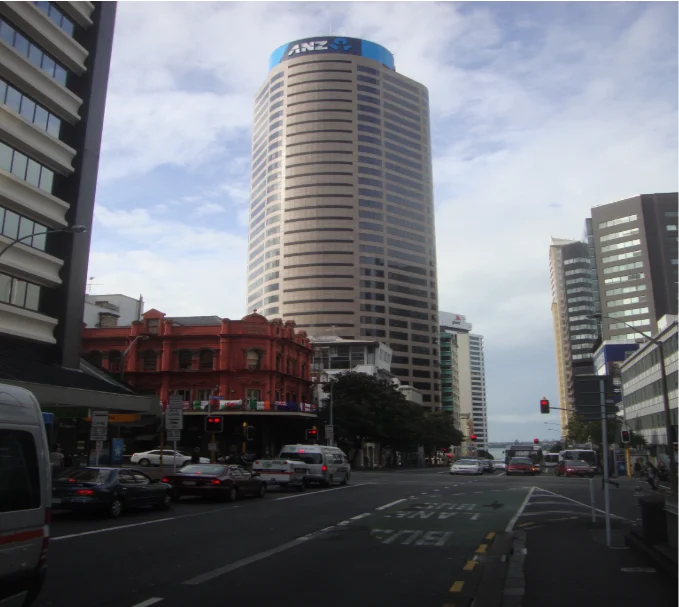
Figure 1: Auckland’s ANZ Center, 11 October 2011. Schwede66, Wikimedia Commons, CC BY-SA 4.0.
The Interest Bill Fell by More Than Interest Receipts
ANZ earned almost NZD 1.5 billion less in interest than it did in FY2025. Ordinarily, that would be a considerable hole to fill. But the bank was also paying less interest on its funding. That bill fell by NZD 1.61 billion.
ANZ therefore kept NZD 4.586 billion in net interest income, up NZD 113 million. Fees and commissions contributed a further NZD 30 million of growth. Had the rest of the income statement stood still, the bank would have entered the year-end expense calculation in a stronger position.
The line that changed the result was other income. It dropped from NZD 429 million to NZD 295 million. By the time ANZ added up all three income lines, the annual gain was just NZD 9 million.
| New Zealand business, NZD million | FY2025 | FY2026 | Change |
|---|---|---|---|
| Net interest income | 4,473 | 4,586 | +113 |
| Net fees and commissions | 487 | 517 | +30 |
| Other income | 429 | 295 | −134 |
| Total operating income | 5,389 | 5,398 | +9 |
A Court Case Changed the Expense Account Before Any Final Settlement
In May 2026, the High Court issued a summary judgment in a representative proceeding involving the bank. ANZ recorded NZD 125 million in its accounts as its estimate of the maximum potential liability. No equivalent provision appeared in the previous year.
The distinction between recording the expense and paying it matters here. The NZD 125 million counted against FY2026 profit. It was not a final settlement. When the accounts were released, ANZ had appealed, the representative plaintiffs had cross-appealed and the substantive proceedings were on hold.
There was a quieter increase in the technology budget. Subscription licences and outsourced services cost NZD 265 million, against NZD 214 million a year earlier. That NZD 51 million difference accounted for the whole net rise in technology expenses. Salaries and related costs, by comparison, barely moved: NZD 1.032 billion against NZD 1.030 billion.
The court provision and the increase in technology expenses together came to NZD 176 million. They also leave different questions for next year: one depends on a legal outcome; the other concerns services the bank uses to operate.
A Credit Release Last Year Made This Year’s Charge More Noticeable
Credit costs affected both sides of the annual comparison. In FY2025, ANZ released NZD 25 million of an earlier allowance for expected losses. That lifted profit. In FY2026, it recorded a NZD 42 million charge instead.
For readers checking the ANZ NZ profit 2026 figure, the year-on-year effect was NZD 67 million. The bank lost the benefit of last year’s release as well as taking this year’s charge. It would be wrong, though, to describe that NZD 67 million as loans that customers failed to repay during FY2026. It is the difference between two years’ impairment entries.
At that point, pre-tax profit was down NZD 238 million. A lower tax bill narrowed the gap by NZD 65 million, leaving the final after-tax decline at NZD 173 million.
The Larger Loan Book Will Take Time to Show Up in Earnings
A mortgage drawn in late September illustrates the timing. Its outstanding balance appears in the year-end loan figure straight away. Only a few days of interest belong in that year’s income. A larger closing loan book and a smaller annual profit can therefore sit comfortably in the same set of accounts.
What the ANZ New Zealand earnings 2026 figures establish is fairly specific. The bank kept more interest income after funding costs, even as gross interest receipts fell. It also entered the new year with more money out on loan.
Whether that produces a better profit will depend partly on costs that sit well outside lending. This year, the court provision alone was larger than the entire NZD 113 million gain in net interest income.
ALSO READ: Westpac Banking Strategy 2026: Can Business Lending Drive Future Returns?
FAQs
Why Two After-Tax Profit Figures?
ANZ New Zealand earned NZD 2.402 billion. NZD 2.359 billion went to ANZ Group Holdings Limited stockholders and NZD 43 million to non-controlling interests.
How Much Did Costs Rise vs. Income?
In FY2026, operating expenditures climbed from NZD 33.85 to NZD 37.10 per NZD 100 of operational revenue.
Did ANZ Earn a Wider Margin with Higher Net Interest Income?
The numbers represent dollar growth. Readers also need the bank’s average interest-earning assets for the year to calculate a percentage margin.
Was the Legal Provision Included in Credit Losses?
No. ANZ included the NZD 125 million provision in operating expenses. It recorded the NZD 42 million credit impairment charge separately.
Disclaimer:
This article provides general information, not personal financial advice. All amounts are in New Zealand dollars.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.