Nickel Industries Limited (ASX: NIC) has released its quarterly results for the period ended 30 September 2026. The headline looks great. Adjusted EBITDA hit US$125.9m. Record ore sales and record earnings at the Hengjaya Mine in Indonesia did the heavy lifting.
This Nickel Industries ASX news shows where the group’s profit is really coming from. The figures come from the company’s quarterly activities presentation, with filings on the ASX website.
Not everything shone, though. Processing margins slipped, and cash flow turned negative. Here is what happened, and why it matters for the months ahead.
Hengjaya Mine Earnings Growth Powers A Record Quarter
Hengjaya Mine had the best quarter in its history. Adjusted EBITDA reached US$76.9m, up 68% on the June 2026 quarter. That is a second consecutive record. Nickel Industries holds an 80% interest in the mine. Ore sales hit 4.5m wmt, another quarterly record, and climbed 56%.
So why did earnings jump so fast? Volume played a big part. Limonite sales more than doubled, rising 104% to 2,802,477 wmt. Saprolite sales rose 12% to 1,682,693 wmt. Costs fell as well. Unit operating costs dropped 15% to US$18.5/wmt, thanks to more efficient haulage routes. Adjusted EBITDA per wmt climbed 8% to US$17.1/wmt. The EBITDA margin lifted to 46.7%.
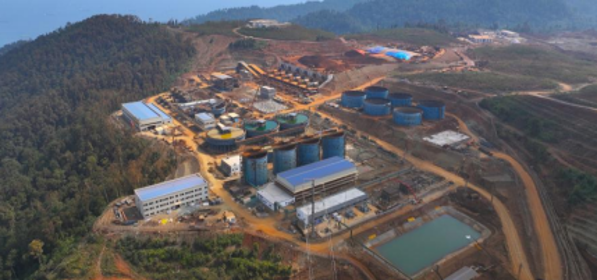
Ore haulage at the Hengjaya Mine supported record sales of 4.5m wmt in the September 2026 quarter. [Nickel Industries Limited]
Mining Numbers That Moved The Needle
A few figures stand out from the mine’s scorecard. Here is how the September quarter compared with June.
- Total production: 6,143,444 wmt, up 49%.
- Overburden removed: 1,433,933 BCM, up 67%.
- Average sale price: US$35.7/wmt, down 6% as limonite made up more of the mix.
- Saprolite price: US$58.1/wmt, up 13%, while limonite eased 2% to US$22.2/wmt.
- Ore grades: saprolite at 1.50% and limonite at 1.09%.
Processing Arms Tell A Tougher Story
The processing side had a harder quarter. The RKEF division produced 27,822t of nickel, flat on June. Sales came in at 26,837t at US$14,408/t Ni, down 1%. Cash costs rose 4% to US$13,054/t Ni. Two things pushed costs up.
The Indonesian Government lifted the nickel ore Mineral Benchmark Price, and the HNI line went through scheduled maintenance. RKEF Adjusted EBITDA fell 33% to US$40.7m. Steady NPI pricing and firm stainless steel demand softened the blow.
The HPAL arm delivered a milestone. ENC produced its first mixed hydroxide precipitate (MHP) and its first nickel cathode. MHP output totalled 4,840t Ni and 494t Co, at a cash cost of US$13,943/t. Nickel Industries holds a 46% indirect interest in ENC. HNC distributions reached US$13.0m, up 271%. HPAL Adjusted EBITDA came in at US$8.4m.
Why Cash Flow Slipped Despite The Profit
Strong earnings did not become cash this quarter. Working capital was the main reason.
- Cash flow before growth and debt: (US$12.2m).
- Growth spend: US$50.5m, mostly the ENC working capital loan and Sampala development capex.
- Net debt: US$1,104m, made up of US$450m syndicated loans and US$800m unsecured notes.
- Receivables: higher at the mine and RKEF, with mine sales up 56%.
- Corporate costs: include a US$4.4m advisor fee for Sphere’s 10% ENC acquisition, recoverable from Shanghai Decent.
Guidance Progress And The Road To Year-End
Management has set clear targets for the rest of 2026. Here is how year-to-date progress compares with the FY26 guidance midpoint.
- Mine consolidated sales: 73%, or 10.4M of 14.3M wmt, with an RKAB increase to 19M wmt sought.
- RKEF consolidated sales: 81%, or 85.0kt of 100–110kt Ni.
- HPAL attributable sales: 55%, or 5.8kt of 10–11kt Ni, with ENC sales starting once the IUI arrives in Q4 2026.
- Total capex: 73%, or US$51.0m of US$66–73m.
- Funding: US$245m OCBC-led project finance signed, enabling a dividend recap to shareholders.
Safety stayed solid. The 12-month LTIFR was 0.06, and TRIFR was 0.67, across 17.8M safe man-hours. The company also ranked in the top 20% of Asia Pacific metals and mining peers in the S&P Global CSA.
Also Read: PLS Group US$700M Notes Put Lithium Growth in Focus
Nickel Industries Quarterly Results 2026 FAQs
Q1: What was Nickel Industries’ Adjusted EBITDA for the quarter?
A1: It was US$125.9m for the September 2026 quarter. Hengjaya Mine contributed US$76.9m, up 68%.
Q2: Why did group cash flow turn negative?
A2: Cash flow before growth and debt was (US$12.2m). Receivables and inventory movements drove it, with mine sales up 56%.
Q3: When will ENC begin sales?
A3: ENC sales start once the IUI is received, expected in Q4 2026. HPAL attributable sales stand at 5.8kt against 10–11kt guidance.
Q4: How much debt does Nickel Industries carry?
A4: Net debt is US$1,104m, including US$450m syndicated loans and US$800m unsecured notes. The US$245m ENC debt is excluded.
Disclaimer:
This article summarises Nickel Industries’ quarterly activities presentation for general information only. It is not financial advice or an offer to buy or sell ASX: NIC securities. FY26 guidance, including sales, capex, IUI timing and RKAB approvals, relies on forward-looking statements and uncertainties. Actual results may differ materially. Readers should check ASX announcements and consult a licensed adviser before investing.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.