Someone who bought Perseus Mining shares a year ago faced a different decision from someone considering them now.
The supplied October review used A$4.95 as its starting price and A$6.38 as its later quote. Between those points, shareholders received more information about earnings, capital returns and the company’s development plans.
The shareholder register adds another part of the picture. It identifies disclosed interests in the business, although it cannot explain every holder’s reasons for owning it.
That distinction matters when a rising share price and well-known institutional names appear together.
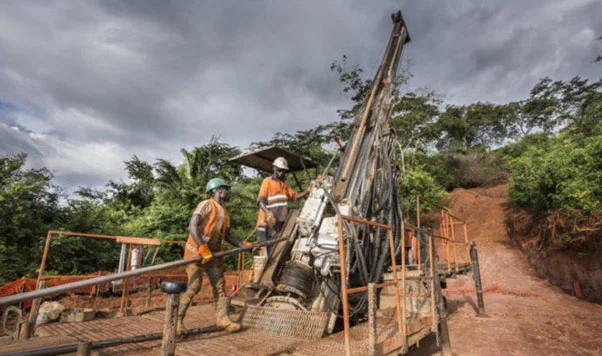
Figure 1: Processing facilities at Perseus Mining’s Yaouré gold operation in Côte d’Ivoire. Historical project photograph. Credit: Lycopodium.
Why Named Institutional Holders Deserve a Closer Look?
Perseus’s annual report lists the following substantial shareholders, with information applicable as at 31 July 2026.
| Disclosed substantial shareholder | Ordinary shares |
| Australian Super | 110,278,060 |
| Van Eck Associates Corporation | 88,260,204 |
| State Street Corporation | 86,536,477 |
| The Vanguard Group, Inc | 81,193,631 |
| Macquarie Bank Limited | 66,500,339 |
These are dated disclosures, not a live ownership register. Later notices may change the picture.
The names establish that large investment organisations have held substantial interests. They do not establish a shared valuation or a common investment horizon.
Nor should the optimistic and cautious scenarios in the supplied review be attributed to these holders.
A Nominee Name Does Not Reveal the Underlying Investment View
The annual report’s separate list of largest registered shareholders includes HSBC Custody Nominees, JP Morgan Nominees and Citicorp Nominees.
A nominee account can hold shares for underlying clients. Reading its balance as one investor’s deliberate bet on Perseus would therefore be misleading.
A sound Perseus Mining stock analysis keeps those distinctions visible. Ownership data can help explain the register; it cannot substitute for an assessment of the business or reveal every investor’s intentions.
The Higher Share Price Changes the Valuation Question
These are historical reference points. The ASX PRU share price quoted here is not a live market price, and the scenario values are not guaranteed outcomes.
| Measure from the supplied October review | Figure |
| Starting share price | A$4.95 |
| Later quoted share price | A$6.38 |
| Optimistic scenario valuation | A$5.80 |
| Cautious scenario valuation | A$4.26 |
| Price increase between the two quotes, calculated | Approximately 28.9% |
A higher price leaves a buyer asking a harder question: how much further improvement is already being paid for?
Revenue Growth Needs to Be Read Alongside Margins
The half-year comparison in the supplied review showed revenue rising from US$666.296 million to US$875.447 million.
Net margin also improved, from 28.9% to 30.2%.
| Half-year measure in the supplied review | Earlier comparison | H2 2026 |
| Revenue | US$666.296 million | US$875.447 million |
| Net margin | 28.9% | 30.2% |
Revenue increased by approximately 31.4%, while net margin gained 1.3 percentage points. These are the review’s half-year figures, not full-year totals.
That combination supports the argument that stronger sales translated into improved profitability. It does not, by itself, prove that mining costs fell. Gold prices, sales volumes and other financial items can influence the result.
The follow-up question is whether those margins can be maintained under less favourable selling prices.
Colitco’s coverage of Emerald Resources’ Okvau performance examines a related issue: how operating results and development spending affect the cash available for growth.
Buybacks Need to Be Judged Against the Money Still Required
The supplied review refers to completed share buybacks. For continuing shareholders, a reduction in shares outstanding can increase their proportional interest in the company.
But the company also spends cash to achieve that reduction. A producer developing another mine needs to consider construction spending, operating requirements and its financial reserves alongside shareholder returns.
The existence of a buyback is therefore only the beginning of the assessment. Its scale, purchase price and effect on the remaining balance sheet matter too.
Colitco’s discussion of ASX dividend stocks and cash flow provides further context on assessing distributions against a company’s capacity to fund them.
What to Expect Next?
Perseus operates Edikan in Ghana and Sissingué and Yaouré in Côte d’Ivoire. Its development plans include Nyanzaga in Tanzania and the CMA Underground project at Yaouré.
The company’s operations overview identifies January 2027 as the expected first-gold date for Nyanzaga and Q3 FY2027 for the commencement of CMA Underground production. These remain forward-looking milestones.
Those projects help explain the growth argument in the supplied review. They also leave work to be completed.
The relevant updates will therefore include remaining expenditure and commissioning progress, followed by actual production and costs.
ALSO READ: Alkane Resources Delivers 40,740 AuEq Ounces While Maintaining FY2027 Guidance
FAQs
Q1. Which institutions appeared in Perseus’s substantial shareholder disclosures?
Ans. The annual report’s 31 July 2026 snapshot named Australian Super, Van Eck, State Street, Vanguard and Macquarie Bank.
Q2. Is A$6.38 the current Perseus share price?
Ans. It is the quote in the supplied October review. It should not be treated as a live price.
Q3. Are A$5.80 and A$4.26 official company price targets?
Ans. No. They are valuation scenarios discussed in the review, based on different assumptions.
Q4. Is the stock a good investment based on its institutional ownership?
Ans. The entry price, the earnings outlook, the development spending and the operating risks still have to be evaluated.
Disclaimer
The information in this article is general in nature and is not personal financial advice. Ownership figures and market quotes are as of the stated dates. Project schedules and valuation scenarios are uncertain. Investors are advised to perform their own research and consult with their financial advisor before making any investment decision.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.