The Macmahon Holdings Aspect Engineering deal would extend the contractor’s involvement in mining projects, from early design through to operations and maintenance.
Announced on 18 September 2026, the agreement covers 100% of Aspect Engineering Solutions and its associated subsidiaries. Macmahon expects completion during the current calendar year, subject to regulatory clearances and other conditions.
For shareholders, the proposal combines an expansion of services with a staged payment structure. Management forecasts an immediate underlying earnings-per-share benefit, although the acquisition has not yet completed.
The commercial question is whether Aspect’s engineering expertise can generate more business when supported by Macmahon’s scale, client relationships and project delivery infrastructure.
Buying Capabilities Across the Project Lifecycle
Macmahon’s existing activities span surface mining, underground mining and civil infrastructure. Aspect would add front-end engineering, detailed design, project delivery, minerals processing, and operations and maintenance capabilities.
Together, those services could allow the group to engage with clients before a mine enters construction and remain involved through later operating stages.
The proposed acquisition supports Macmahon’s FY27–FY31 growth strategy. Its existing mining and infrastructure businesses provide context for the capabilities Aspect would complement.
This is a broader service offering, rather than an announcement of newly secured integrated contracts. Revenue benefits will depend on clients choosing to award additional work.
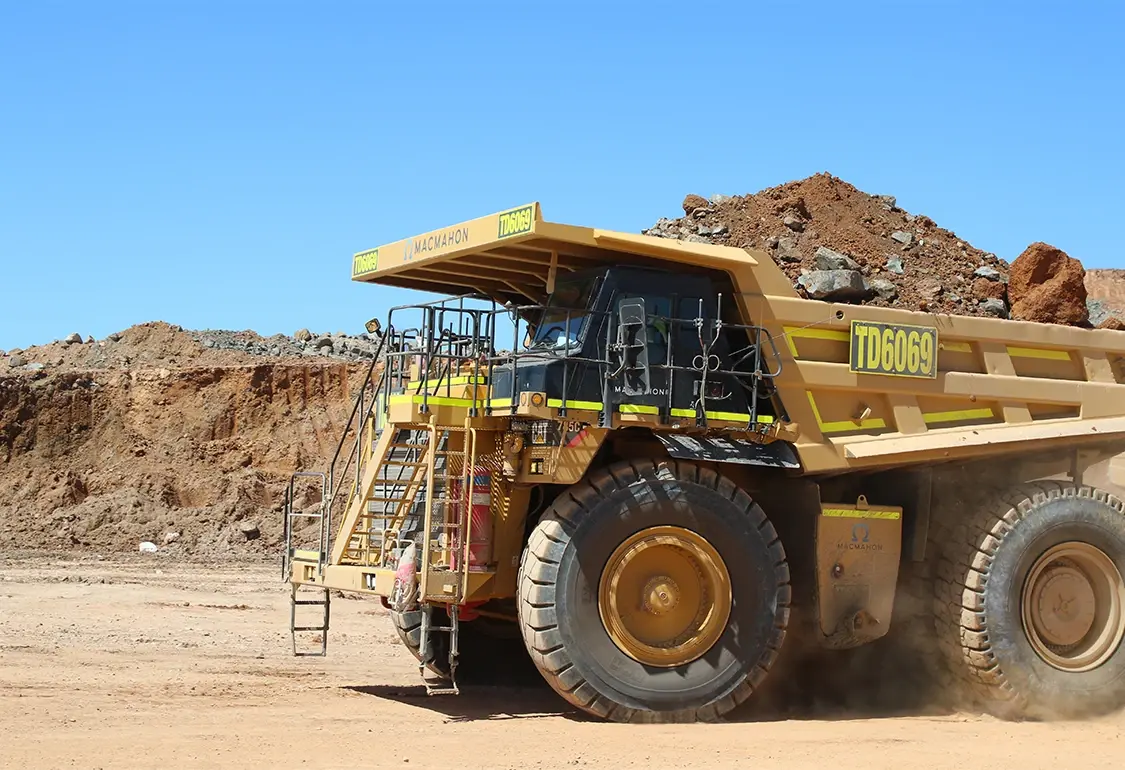
Figure 1: Macmahon haulage equipment at Greenbushes, illustrating its established mining services operations. The photograph does not depict an Aspect project. Image credit: Macmahon.
What Aspect Brings to the Group
Aspect generated approximately A$75 million in revenue and A$15.2 million in earnings before interest and tax during FY2026. These figures are unaudited.
The business employs more than 295 people directly and serves more than 50 active clients across resources, infrastructure and energy.
Its work covers lithium, gold, iron ore, industrial processing and energy infrastructure. Perth operations are supported by a licensed engineering and support hub in Vietnam, providing additional design and resourcing capacity.
| Aspect measure | Disclosed position |
| FY2026 revenue | Approximately A$75 million |
| FY2026 EBIT | A$15.2 million |
| Direct employees | More than 295 |
| Active clients | More than 50 |
| Contracted backlog at 31 May 2026 | Approximately A$66.6 million |
| Unweighted pipeline at 31 May 2026 | Approximately A$225.8 million |
The backlog represents contracted work. The unweighted pipeline represents opportunities and should not be treated as secured revenue.
Where Management Expects the Benefits
The MAH mining synergies expansion case rests on complementary services and access to a larger operating network:
- Earlier engagement: Engineering and feasibility work could introduce Macmahon to clients before mining contracts are awarded.
- Longer relationships: Design, construction, operations and maintenance create opportunities to remain involved across project stages.
- Broader delivery capacity: Aspect would gain access to Macmahon’s infrastructure, financial capacity and operational footprint.
- A different revenue mix: Management expects greater participation in services requiring less capital and offering higher margins.
These are expected advantages. The announcement does not provide a separate quantified synergy target or confirm that these benefits have already been achieved.
How the Purchase Payments Are Structured
The A$75 million headline enterprise value is quoted on a debt-free, cash-free basis. It equates to approximately five times Aspect’s FY2026 EBIT.
Macmahon will pay A$30 million upfront on completion, subject to customary net working capital adjustments.
A further A$30 million consists of retention-linked payments of A$6 million annually over five years.
Earn-out payments would total A$15 million if base-case performance hurdles are met, increasing to A$30 million if outperformance hurdles are achieved over three to five years.
Adding the disclosed components produces A$75 million under the base-case earn-out and up to A$90 million under the outperformance case, before applicable adjustments. The headline valuation and maximum potential payments therefore describe different measures.
Why the Accounting Treatment Matters
The deferred payments carry an accounting distinction that shareholders should understand.
Macmahon says retention and earn-out amounts will be treated as employee expenses over the relevant three-to-five-year period. They will not be allocated to the fair value of the business acquired in FY2027.
Consequently, investors need to consider both the acquisition’s operating contribution and the expenses associated with retaining people and rewarding performance.
Funding will come from existing cash reserves. Macmahon also retains discretion to settle future retention and earn-out payments in shares.
If that option is used, the share number would depend on the volume-weighted average price over the preceding 30 trading days.
Reading the Earnings Forecast Carefully
Macmahon expects approximately 6.2% underlying EPS accretion before synergies and identifies a base-case internal rate of return of 40.4%, also before synergies.
Both are transaction forecasts, not achieved results.
The release compares the acquisition’s approximately 5.0-times EBIT valuation with Macmahon’s referenced trading multiple of 11.4 times at 30 June 2026. That comparison helps explain management’s investment case but does not establish a guaranteed valuation uplift.
Chief executive Michael Finnegan said, “Importantly, the investment case is attractive on a standalone basis.”
For the Macmahon acquisition mining services strategy, that makes Aspect’s own earnings performance an important test alongside any future cross-selling opportunities.
Figure 2: Macmahon personnel reviewing project information. Image credit: Macmahon.
How Aspect Will Be Integrated
Macmahon intends to preserve several parts of Aspect’s operating structure while introducing group support:
- Business identity: Aspect will operate as a standalone business and retain its brand.
- Management continuity: Its executive management will remain with the business.
- Workforce retention: The existing workforce is also expected to remain.
- Group controls: Macmahon will progressively introduce governance, systems, project controls and workforce support.
The approach seeks to maintain Aspect’s client relationships while adding the oversight and resources of a larger owner.
Successful integration will require those controls to support delivery without disrupting the business being acquired.
What Could Determine the Outcome
The Macmahon Holdings Aspect Engineering deal depends on more than completing the share purchase.
Aspect must continue delivering contracted work, retaining expertise and winning projects. The size of its pipeline indicates opportunity, but does not establish the timing or likelihood of contract awards.
The payment structure links part of the financial commitment to retention and future performance. It does not eliminate execution risk.
Likewise, the expected EPS benefit requires the underlying assumptions to hold. Subsequent financial reporting will be needed to assess earnings delivery, deferred expenses and cash commitments together.
Milestones Investors Should Monitor
The most useful follow-up disclosures will address:
- Completion: Confirmation that regulatory clearances and transaction conditions have been satisfied.
- Earnings contribution: Aspect’s actual performance against the acquisition assumptions.
- Contract conversion: Evidence that pipeline opportunities become awarded work.
- Payment obligations: Progress against retention and earn-out conditions, including settlement in cash or shares.
- Commercial benefits: Identifiable contracts or client opportunities arising from the combined capabilities.
Macmahon’s ASX announcement register provides a primary-source location for monitoring those developments.
Outlook
Macmahon is seeking a larger role in the work surrounding mine development and operation. Aspect supplies capabilities that fit that ambition, backed by an existing workforce, client base and earnings record.
The next test is delivery: completing the transaction, preserving Aspect’s performance and demonstrating that the expanded offering attracts business.
FAQ
Has the acquisition completed?
No. Completion was expected during calendar 2026, subject to conditions.
Will Aspect retain its name?
Yes. Macmahon intends to retain its brand and leadership.
Are the earnings benefits confirmed?
No. EPS accretion and investment returns remain management forecasts.
Also Read: Why Franco-Nevada Just Put Another A$200m on Minerals 260
Disclaimer
Prepared for Colitco for general information, based on the supplied company announcement. This article is not investment advice. Acquisition completion, earnings forecasts and expected benefits remain subject to conditions and business risks. Readers should review company disclosures independently before making financial decisions.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.