The PDI Gold Bankan permits were signed by presidential decree on 16 November, and the ASX release followed the next morning. The company applied on 31 January 2025. That is more than 21 months for a piece of paper.
Bankan is the headline project. Mansounia, a deposit at the operating Kiniéro mine, is the quicker win.
The Bankan Gold Project permits ended a very long final stage
The June 2025 feasibility study, issued when the company was still Predictive Discovery, called the review a final stage. It said the permit would arrive “in the near future”. Nearly 17 months followed.
Bankan’s permit is held by Hamana Gold SA, covers 98.6km2 and runs for an initial 15 years. Guinea is entitled to a 15% interest in the permits under its Mining Code.
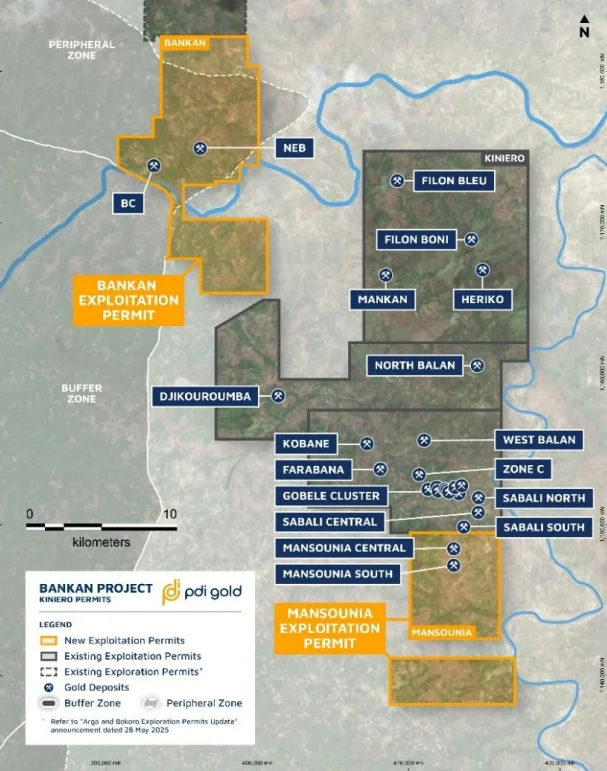
Bankan, Mansounia and existing Kiniéro exploitation permits. [PDI Gold]
One slip sits in the release. The second Mansounia permit is listed at 26.5m2, which almost certainly means 26.5km2. The decrees themselves will settle it.
Ounces need a footnote too. Inside the Bankan permit sit 5.37Moz of resources: 4.14Moz indicated and 1.23Moz inferred. The 5.53Moz headline from the feasibility study also counted Fouwagbe and Sounsoun, which sit on the Argo permit that Guinea announced it was revoking in May 2025. The release says nothing about where that stands.
Two more things are missing. The feasibility study said a mining convention would be negotiated after the grant and ratified by Guinea’s legislature. The release never mentions it. Nor does it say whether the study’s valuations already carry the state’s 15%.
Mansounia is low grade, near surface and quick to start
Mansounia’s reserve is 19.5Mt at 0.77g/t for 0.48Moz. Bankan’s is 51.6Mt at 1.78g/t. Different beasts.
| Bankan | Mansounia | |
|---|---|---|
| Permit holder | Hamana Gold SA | Sycamore Mine Guinee SAU |
| Permit area | 98.6km2 | 44.7km2 and 26.5km2 (release prints “m2”) |
| Initial term | 15 years | 15 years each |
| Ore reserve | 51.6Mt at 1.78g/t, 2.95Moz | 19.5Mt at 0.77g/t, 0.48Moz |
| Indicated resource | 83.7Mt at 1.54g/t, 4.14Moz | 29.3Mt at 0.72g/t, 0.68Moz |
| Inferred resource | 16.8Mt at 2.28g/t, 1.23Moz | 43.6Mt at 0.71g/t, 1.00Moz |
Table 1: Bankan and Mansounia permits and reserves at a glance. [PDI Gold]
Cheap ounces still count. The deposit is near surface and has a low strip ratio. That means little waste rock per tonne of ore. Grade control drilling is finished, the first pit stages are designed, and mining preparation starts straight away.
At Kiniéro’s 6Mtpa plant, 19.5Mt is about three years of feed. In the September quarter that plant ran ore at 0.69g/t. Low-grade stockpiles filled in while mined volumes were down. Fresh pit ore at 0.77g/t is a modest step up.
A mid-2028 first pour leaves a tight build window
The feasibility study planned a two-year build starting in the second quarter of 2026. The permit arrived about six months after that. PDI Gold’s first gold in 2028 is still targeted for mid-year, about 19 or 20 months from the decree. The study allowed 24.
That is hard to square with the underground plan. The study has the GBE pit running about nine months to open a portal, then roughly 15 months of decline work (the sloping tunnel down) before the first stope ore. Two years, on its own. Either the sequence overlaps more, or early open pit ore carries more of the load. The optimised schedule due in early 2027 should say which.
With the exploitation permits granted, the board has told management to speed up procurement, engineering and land compensation. Plenty is already moving. US$18m in down payments has gone on the SAG and ball mills and the 40MW power station. Per the September quarter presentation, process plant engineering was about 20% done at the end of September. Completion is targeted for the second quarter of 2027.
Kiniéro’s on-time build helps. Bankan adds an underground mine with paste fill, plus a filtered tailings facility inside the peripheral zone of a national park.
A permit also starts a clock. In 2025 Guinea pulled bauxite licences from Emirates Global Aluminium and Kebo Energy, citing inactivity and non-compliance. Schedules slip in mining all the time, as Capstone Copper’s delayed Pinto Valley restart showed. In Guinea, the state is watching the clock too.
The money looks fine, but the capex number is old
The release does not expect the US$463m capital cost to rise, and says initiatives are chasing cuts. That figure uses Q1 2025 pricing. Per the study, it also leaves out escalation, financing and corporate costs. Flat after nearly two years deserves a hard look when the update lands.
Funding is the stronger side. Cash and bullion hit US$405m at 30 September, and the company says Bankan will be paid for from cash and mine cash flow. About US$81.5m of that is restricted. Usable cash and bullion is roughly US$323m, against a US$463m build. FNArena’s summary of Canaccord Genuity’s note also lists US$130m of debt.
That puts the load on the mines. Last quarter’s free cash flow was US$128m, at a realised US$4,227/oz against group all-in sustaining cost (AISC, the full cost of making an ounce) of US$1,390/oz. Sales of 67koz beat the 53koz poured because June-quarter bullion was sold, so that quarter flatters the run rate. For another ASX gold producer holding guidance, see Alkane Resources’ latest production update.
Odd mix: the price side of the study is stale in the good direction, and the cost side may be stale in the bad one. The spot case used US$3,300 gold, about US$930 below that realised price. The company’s own rule of thumb adds about US$140m of value per US$100/oz.
In late October the whole company was worth about A$3.8bn on the market. The study’s spot case gave Bankan alone A$4.5bn, at the study’s 0.65 exchange rate. Different yardsticks, but the gap was wide. The market was charging for permit risk, and part of that charge now comes off.
Permit risk has mostly cleared. Build risk has just started. This ASX PDI Bankan update settles the first and says little on the second, so the early 2027 schedule and capex release is the date to watch.
For a larger ASX producer’s growth plans, see Colitco’s note on Northern Star’s gold growth pipeline. More company updates sit under Colitco’s mining announcements.
Also Read: Capstone Copper Guidance Cut: Pinto Valley Restart Slips
FAQs
Q: What permits did PDI Gold receive?
A: Exploitation permits for Bankan and Mansounia, each with an initial 15-year term.
Q: When is first gold at Bankan due?
A: Mid-2028, with an updated schedule promised in early 2027.
Q: What will Bankan cost to build?
A: The 2025 study says US$463m, with a fresh estimate due in early 2027.
Q: How will PDI Gold fund Bankan?
A: From existing cash and mine cash flow, according to the company.
Q: How much of the permits does Guinea get?
A: A 15% interest under the Mining Code.
Disclaimer:
This article is general information only and is not financial product advice. It does not consider anyone’s objectives, financial situation or needs. Mining investments carry risk, including loss of capital. Forward-looking figures come from company announcements and may change. Seek advice from a licensed adviser before making an investment decision. Colitco LLP accepts no responsibility for any loss arising from reliance on this article.
Luke Carlino is a seasoned Copywriter, Content Strategist, and Social Media Manager specialising in Mining, Finance, and Business journalism. With more than a decade of industry experience, he brings rigorous editorial standards and commercial acuity to every project.